ATTENTION: For Those who are serious about Getting Pre-Qualified FAST!
Bill Rapp, Mortgage Originator: NMLS 228246
"Brokers Are Better.
Better Pricing, Better Service!"
Subscribe To My List Below To Get Your Mortgage Quote Now!
Simply enter your name and email below:
WITH PROVEN STRATEGIES & PROVEN RESULTS
HERE'S WHAT MY CLIENTS SAY:
What People Are Saying:
Excellent Service
Bill is an exceptional loan officer. He helped us to purchase our home with very personal and professional service. He helped us navigate the whole process from start to closing without any problems. We didn't think we're qualified to purchase a house, but Bill went above and beyond to find a way to help us achieve our goal. He always responded very quickly with our requests, he would come back with different options with comparison chart to clearly indicate how much we need for down payment, monthly payments, interest rates, closing costs etc.
We would highly recommend Bill to anyone in need of lending services. In fact, we have already recommended Bill to one of our friends on purchasing a house.
--- David Chan - Houston, TX
Bank Statement Lending!
William Rapp of Network Funding, L. P. was very professional and I felt comfortable in dealing with him. I will definitely recommend him to family and friends.
--- Ian F - Missouri City, TX
Professionalism - Expert In Home Style Loan
Bill is an expert in the topic, his explanations and online material make a difference and he is always there from the beginning to the end. He is committed to make thing happen.
--- Felipe Caldern & Carolina Angel Gutierrez
Great Service!
Bill Rapp's handling of our loan (even though out of state) was unparalleled to any service I have been through prior, including 3 different real estate transactions and multiple refinances. Extremely quick close, with great options and flexibility for my families needs. All around A+
--- Chris & Beth Sheehan - San Jose, CA
Knowledgeable and Responsive!
Bill was a pleasure to work with and he made the loan process fairly easy. He answered all questions I had very quickly and was straight forward in doing it. I would recommend Bill to others.
--- Wes Brady - Richmond, TX
Very professional and always returned our calls!
Bill takes a lot of pride in his job and is very dependable. They were very patient and understanding. He went out of his way and explained all my questions and concerns. They were very professional and returned my phone calls and emails. He did a great job and I fully recommend him.
--- Therese, Malcom & Shirley Teixeira - Katy, TX
Great Job!
Bill helped us out from beginning to end of loan process. The loan closed in a timely manner as Bill worked hard with bank to get our to the final steps.
--- Kamal & Theresa Wilson - Hartford, CT
Avid Problem-Solver and Absolute Pleasure to Work With!
Bill Rapp worked very hard to ensure that we closed our loan and were able to move into our new home. He always had alternatives to any problems we encountered while closing. He worked with us from the beginning identifying solutions to any problems that we were having. He was an absolute pleasure to work with!
--- Nikita Rayani & Sanit Tejani - Houston, TX
Awesome to work with!
Being a first-time buyer I came in with lots of questions and concerns. Bill was always available for any questions I had and answered everything to my satisfaction. Bill made the loan process so painless that I could still concentrate on other things. We ended up closing early which made things even better. If you are in need of a lender and want someone who is very approachable and stays on top of your loan then Bill is your guy.
--- Cesar Raya - Richmond, TX
Loan Declined by my bank, and he saved the day!
Bill, did an amazing job helping me close on my house. He took the reigns and reassured me the best route to take to help close. He was accountable, thorough and trustworthy. I will continue to work with Network Funding, L.P. when it comes to home buying in the future because of the quality of service Bill gave.
--- Jacob Smith - Boerne, TX
Bill Rapp Will Definitely Make It Happen!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Corinne Wilson - Roselle, NJ
Knowledgeable, Honest, Trustworthy, and Reliable!
"I will definitely keep you in mind. If anyone I know needs financing, I will send them your way!"
--- Jon & Andrea Saleem, CRPC Financial Advisor - Houston, TX
Best Dam Mortgage Guy a man could know!
"Hands down the best loan experience to date!"
--- Gabe & Chelsea Jackson - Pearland, TX
Phenomenal, Hard Working and Never Quits!
Had a stupid foreclosure that could have been avoided if ex’s attny would have sent my buy out offer. So Bill was able to push this through with a 4 year foreclosure. He worked his butt off, was very diligent with his communication; and was very professional talking to me even when I was screaming and/or crying at him. Highly recommend this lender. He really go to the ends of the earth to help you!
--- Liz Keeter - Harlingen, TX
Exceptional customer service!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Isha Lopez & Mauricio Garcia - Houston, TX
Service with a capitol S
Bill went above and beyond at every turn. He worked late on Saturday, he worked late all the time. We wanted to close ASAP and he really helped make it happen for us.
--- Jeff & Wendy Heger - Houston, TX
Best Buying Experience!
I would would highly recommend going with Network Funding LP. As a first time home buyer I didn't know what to expect. Bill Rapp was very helpful in answering all my questions and guided me through all ghe steps. I couldn't have asked for a better buying experience!
--- Tabitha Turner - Humble, TX
Would recommend him and use him again!
Very involved and professional . Kept me informed and up to date on everything that was going on Went with me closing and was very helpful and knowledgeable.
--- Kathy Ward - Houston, TX
Great experience!
Well I meet bill back in December 2016 he got recommended by my real estate agent we had a house in sight and started the process to get approved but we fail due to my work history and credit bill told me not to give up and put me in contact with a credit repair company they help me bring my score up and bill walk me thru the process of getting a new line so this time around we got approved before looking for our house after we found it we still had a couple of hick up but with bills help on Sunday 6-18-17 to be exact Father's Day bill called me to give me the great news that we had got approved and the closing date was as scheduled bill was more than just a lender to my family he became a friend and I'm alway going to have him in mind for any other financial situation.
--- Alejandres Felimon - Richmond, TX
I really liked his attitude!
I wouldn't usually say this but the way he had handled my mortgage was really pleasant. I personally enjoyed the time spent with him while we discussed feasible rates. He's a great man with a great personality and he offered really low interests as well. Definitely recommend him to others.
--- Tom Troiano - Atlantic City, NJ
He's nothing short of a miracle!
I'm a self-employed businessman and had him figure out the mortgage of the house after 30% down payment. The interest rates I received were incredibly low given what I had thought of earlier. One other important thing to note was that I hadn't really taken any loans earlier, so I had no credit history. He helped me out with all that as well so I can't really call him anything else but a miracle.
--- Fran Suarez - Cleveland, OH
He's really helpful!
I made a bid to him and the very same day he gave me an offer which I couldn't resist. It was too intimidating with those incredibly low interest rates and all, thoroughly recommend him.
--- Kenny Mickle - Houston, TX
Expeditious!
Bill was very expeditious and made it real easy going through the loan process. I felt he was on top of things.
I deal with investment properties and will more than likely call on him again.
--- Wayne King - Pensacola, FL
Bill was great!
Bill made us feel like a friend all the way thru the process. He was patient and explained everything he needed clearly. He was available ANYTIME we had questions or needed more information. Hopefully we won’t go thru this process again anytime soon, but if we do - we’d choose Bill! =)
--- Barbra & Nick Grimmer - Austin, TX
Great broker!
Bill was a great broker to work with. As first time home buyers we had many questions about the process, Bill took the time to help us even calling us back on weekends with answers. I would not hesitate to recommend him to anyone looking for a broker to work with.
--- Murray & Lisa Turner - Pensacola, FL
Outstanding service!
I couldn't have been more pleased with Bill's level of service. He made what is typically a lengthy, arduous process far quicker and easier at every turn. I'm extremely comfortable recommending Bill to friends and family, and will definitely utilize his services again!
--- Jim Lipari - Austin, TX
Renovation Mortgage Specialist
Two little-known home renovation mortgage programs offer solutions for buyers and homeowners who want to renovate.
Fannie Mae and the Federal Housing Administration have home renovation mortgage programs that allow buyers to borrow based on what the house is expected to be worth after the home rehab is completed. Homeowners can also use both programs to refinance their existing mortgage plus the renovation costs into one loan.
FHA's 203(k) program and Fannie's HomeStyle Renovation Mortgage have been around for years. In the old days -- when most borrowers could easily get second mortgages or generous credit lines to pay for renovations -- these loans weren't as appealing as they are today.
Home renovation loans are in Demand !
"A couple years ago, there wasn't as much demand for these loans," says Bill Rapp, a senior loan originator with Network Funding in Houston, who specializes in renovation mortgages. Demand surged in the aftermath of the housing crisis, when borrowers saw them as a way to buy and renovate distressed properties.
How it works Unlike credit lines, these renovation loans require borrowers to show that the money was spent on the house. In the standard FHA 203(k) program, the borrower hires a consultant to assess the construction plan and to perform an inspection before each draw is made. A "draw" happens when a portion of the money is disbursed to the contractor. Borrowers have up to six months to finish the project and are allowed up to five draws. The HomeStyle program does not require a consultant to monitor the work, only an initial and final inspection.
Great for foreclosure hunters !
While rehab loans involve more work than traditional mortgages, they can be a great tool for those who want to buy discounted homes that need repair.
Bill Rapp says he helped a couple who bought a foreclosed house in Houston, TX for $26,000 and borrowed $136,000 to renovate the property. An appraisal estimated the home would be worth about $135,000 after the work was completed. The couple was able to take out an FHA 203(k) mortgage totaling $144,000, which covered the price of the house, renovations, and loan costs, minus a down payment.
But how do you know which loan is best? It depends on the situation.
203(k) vs. HomeStyle .
Those who don't have great credit should probably opt for an FHA 203(k). Most Fannie Mae HomeStyle lenders require a credit score above 660. To get the best rate on a HomeStyle mortgage, borrowers need to have a minimum 740 credit score, Bill Rapp says.
"If you have a 740 score and 10 percent down, a HomeStyle is definitely cheaper," she says. That's because FHA mortgages carry higher mortgage insurance premiums for borrowers who put the least amount down. FHA 203(k) home renovation mortgages have an upfront fee that is rolled into the loan amount. Less-than-stellar credit For borrowers with credit scores lower than 740, it's best to compare estimates, Bill Rapp says.
FHA does not set a minimum score requirement for 203(k) loans, but many lenders require a score of 640 or greater. There are a few exceptions, and some lenders accept scores as low as 580, Bill Rapp says.
Under the FHA's 203(k) program, borrowers can get a mortgage with a down payment as little as 3.5 percent. HomeStyle requires a minimum 5 percent down payment.
The FHA 203(k) program is available only for owner-occupants. The HomeStyle program allows investors.
How much do you need?
Another key factor a borrower should consider when deciding whether to go with a 203(k) or a HomeStyle home renovation mortgage is the size of the loan.
The 203(k) rehab mortgage has to comply with FHA loan limits. The limit varies by county but is $314,827 in most places. In high-cost areas, the limit is as high as $765,525.
You may be able to borrow more with the 203(k) than with HomeStyle if you are borrowing up to the local loan limit.
With a 203(k) loan, borrowers can get up to 110 percent of the home's appraised value, compared with 95 percent with a HomeStyle loan. Both appraisals are based on what the house is expected to be worth after repairs.
What do you want to fix?
FHA's 203(k) rehab loan does not allow borrowers to use the money for luxury items such as adding a swimming pool or a spa, but HomeStyle does.
Borrowers can opt for a streamline FHA 203(k) home rehabilitation loan if they need less than $35,000 and don't have to do any structural repairs or major landscaping work. The streamline 203(k) is similar to a standard 203(k) but is easier to get and involves less paperwork and less bureaucracy, Bill Rapp says. Streamline loans don't require the borrower to hire a consultant.
Call Bill Rapp, The Mortgage Viking, today to discuss your options 281-222-0433.
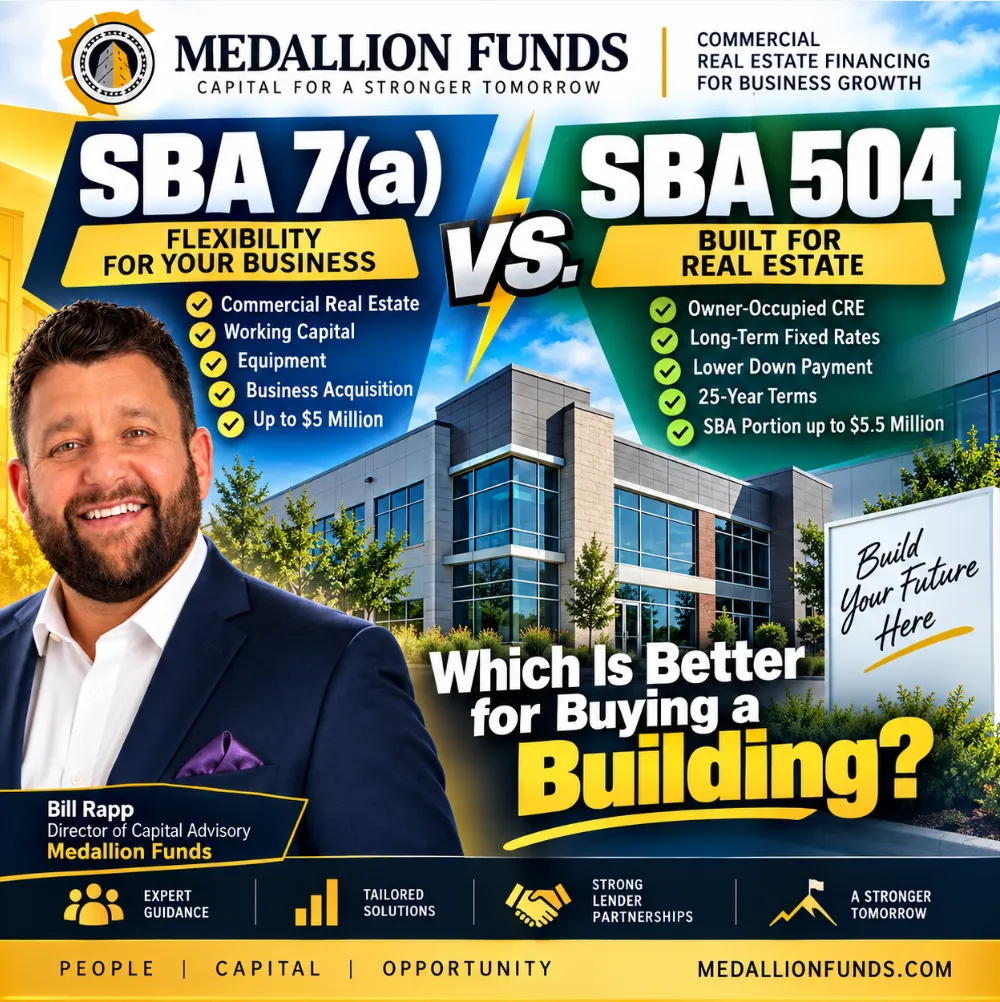
🏢 SBA 7(a) vs. SBA 504 Loans: Which Is Better for Buying Your Business Building? 💰
🏢 SBA 7(a) vs. SBA 504 Loans: Which Is Better for Buying Your Business Building? 💰
🔑 Buying Commercial Real Estate? How to Choose Between an SBA 7(a) and SBA 504 Loan 🏦
SBA 7(a) vs. SBA 504: Which Is Better for Buying a Building?
For many business owners, buying the building their company occupies can be a major step toward controlling occupancy costs, building equity, and creating a long-term real estate asset.
But once you decide to buy, another important decision follows:
Should you finance the property with an SBA 7(a) loan or an SBA 504 loan?
Both programs can finance owner-occupied commercial real estate, but they are designed differently. The better structure depends on the property, total project cost, working-capital requirements, equipment needs, and your broader business objectives.
As of September 2026, SBA 7(a) loans generally offer up to $5 million, while the SBA 504 program provides long-term fixed-asset financing with an SBA/CDC loan component of up to $5.5 million.
Understanding the difference before you make an offer on a building can help you structure the transaction around the financing rather than trying to force the financing around the deal.
What Is an SBA 7(a) Loan?
The SBA 7(a) program is the SBA's primary business loan program. It can finance the acquisition, refinancing, or improvement of commercial real estate, but its usefulness extends well beyond the building itself.
Eligible uses can include working capital, equipment, furniture and fixtures, certain debt refinancing, and complete or partial business acquisitions. A 7(a) loan can therefore be particularly useful when a transaction involves both real estate and other business needs.
For real-estate financing, SBA rules allow terms of up to 25 years, including extensions. Interest rates are negotiated with the lender but remain subject to SBA maximums.
Example: Suppose you're buying a building for your operating company, but you also need funds for renovations, equipment, furniture and working capital. A 7(a) structure may allow you to address several of those needs through a more comprehensive financing package, subject to eligibility and underwriting.
What Is an SBA 504 Loan?
The SBA 504 program is more specifically designed for major fixed assets, including owner-occupied commercial real estate and qualifying long-term equipment.
A typical 504 transaction involves three pieces: a private-sector lender providing a senior loan covering up to approximately 50% of project cost, a CDC/SBA-backed junior loan covering up to approximately 40%, and at least a 10% borrower equity contribution. Actual equity requirements can vary depending on the project and borrower circumstances.
The SBA portion offers long-term, fixed-rate financing, and 25-year maturities are available for real estate.
That combination can make the 504 program particularly attractive when the primary objective is purchasing, constructing, renovating, or expanding an owner-occupied commercial property.
However, there is an important limitation: 504 proceeds cannot be used for working capital or inventory.
SBA 7(a) vs. SBA 504 at a Glance
Feature | SBA 7(a) | SBA 504 |
Primary focus | Flexible business financing | Major fixed assets |
Real estate | Yes | Yes |
Working capital | Yes | No |
Business acquisition | Yes | Generally not the program's purpose |
Equipment | Yes | Qualifying long-term equipment |
Maximum | Generally $5M | SBA/CDC component up to $5.5M |
Real-estate term | Up to 25 years | 25-year option |
Rate structure | Negotiated, subject to SBA limits | SBA/CDC portion is fixed |
Structure | Primarily lender + SBA guaranty | Typically bank + CDC/SBA + borrower |
Best use case | Multi-purpose financing | Fixed-asset-heavy project |
SBA's current program comparison confirms these fundamental differences.
When SBA 7(a) May Make More Sense
Consider 7(a) when the building is only one part of the transaction.
For example, you might purchase a $1.5 million building but also need substantial improvements, equipment, furniture and working capital to move your company into the new location.
Rather than looking only at the real estate, the financing strategy should consider the entire capital requirement.
This flexibility is one of the principal advantages of 7(a).
When SBA 504 May Make More Sense
Now consider a business buying a larger facility where most of the project's capital is going directly into the real estate.
If preserving cash is important and the transaction qualifies for the typical 50/40/10 structure, a 504 loan deserves serious consideration.
The program was specifically designed to provide long-term financing for major fixed assets and may be particularly relevant for office buildings, medical and dental practices, warehouses, manufacturing facilities and other owner-occupied properties.
Don't Assume 10% Down Is Automatic
One of the most common mistakes is seeing an advertisement for "SBA financing with 10% down" and assuming every borrower and property will qualify for that structure.
The typical 504 framework includes at least 10% borrower equity, but actual requirements depend on the transaction.
Similarly, a 7(a) transaction needs to be underwritten based on the business, borrower, collateral, cash flow and lender requirements.
Low down payment is a potential SBA advantage—not a substitute for underwriting.
A Major SBA Change in 2026
Business owners planning larger capital projects should also know about an important recent change.
Effective July 4, 2026, SBA changed its rules so qualified borrowers can potentially access up to $5 million through 7(a) and up to $5 million through 504, for as much as $10 million in combined SBA-backed financing.
That can be especially relevant for capital-intensive businesses that need fixed-asset financing and additional capital for operating or expansion needs.
It does not mean every borrower automatically qualifies for $10 million. Eligibility, underwriting, program requirements and lender approval still apply.
So, Which SBA Loan Is Better for Buying a Building?
The question shouldn't simply be:
"Which SBA loan has the lowest rate?"
Instead, ask:
"Which capital structure best accomplishes what my business is trying to do?"
If you primarily need to acquire a major fixed asset, the 504 structure may deserve closer consideration.
If you need to combine the real estate purchase with working capital, equipment, a business acquisition or other eligible business expenses, 7(a)'s flexibility may be valuable.
And with the 2026 rule changes, some qualified borrowers may even benefit from strategically combining the programs.
Start With the Project, Not the Loan Product
Before choosing 7(a), 504 or conventional commercial financing, determine your complete sources and uses:
Purchase price, renovations, equipment, furniture and fixtures, closing costs, working capital, borrower equity, reserves and future expansion needs should all be considered.
That gives a commercial mortgage advisor the information needed to compare structures instead of simply quoting a loan.
At Medallion Funds, we help business owners evaluate commercial real estate financing based on the entire transaction and long-term objective.
Financing is subject to lender and SBA eligibility, underwriting, program requirements, credit approval and availability. Program terms can change.
Official SBA 7(a) program information
Official SBA 504 program information
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
Main Office:
Medallion Funds
[email protected]
11920 Southern Highlands PKWY Suite 302Las Vegas, NV 89141
Texas Complaint and Recovery Fund Notice
All Rights Reserved Copyright © 2021 - Bill Rapp The Mortgage Viking | NMLS #228246