ATTENTION: For Those who are serious about Getting Pre-Qualified FAST!
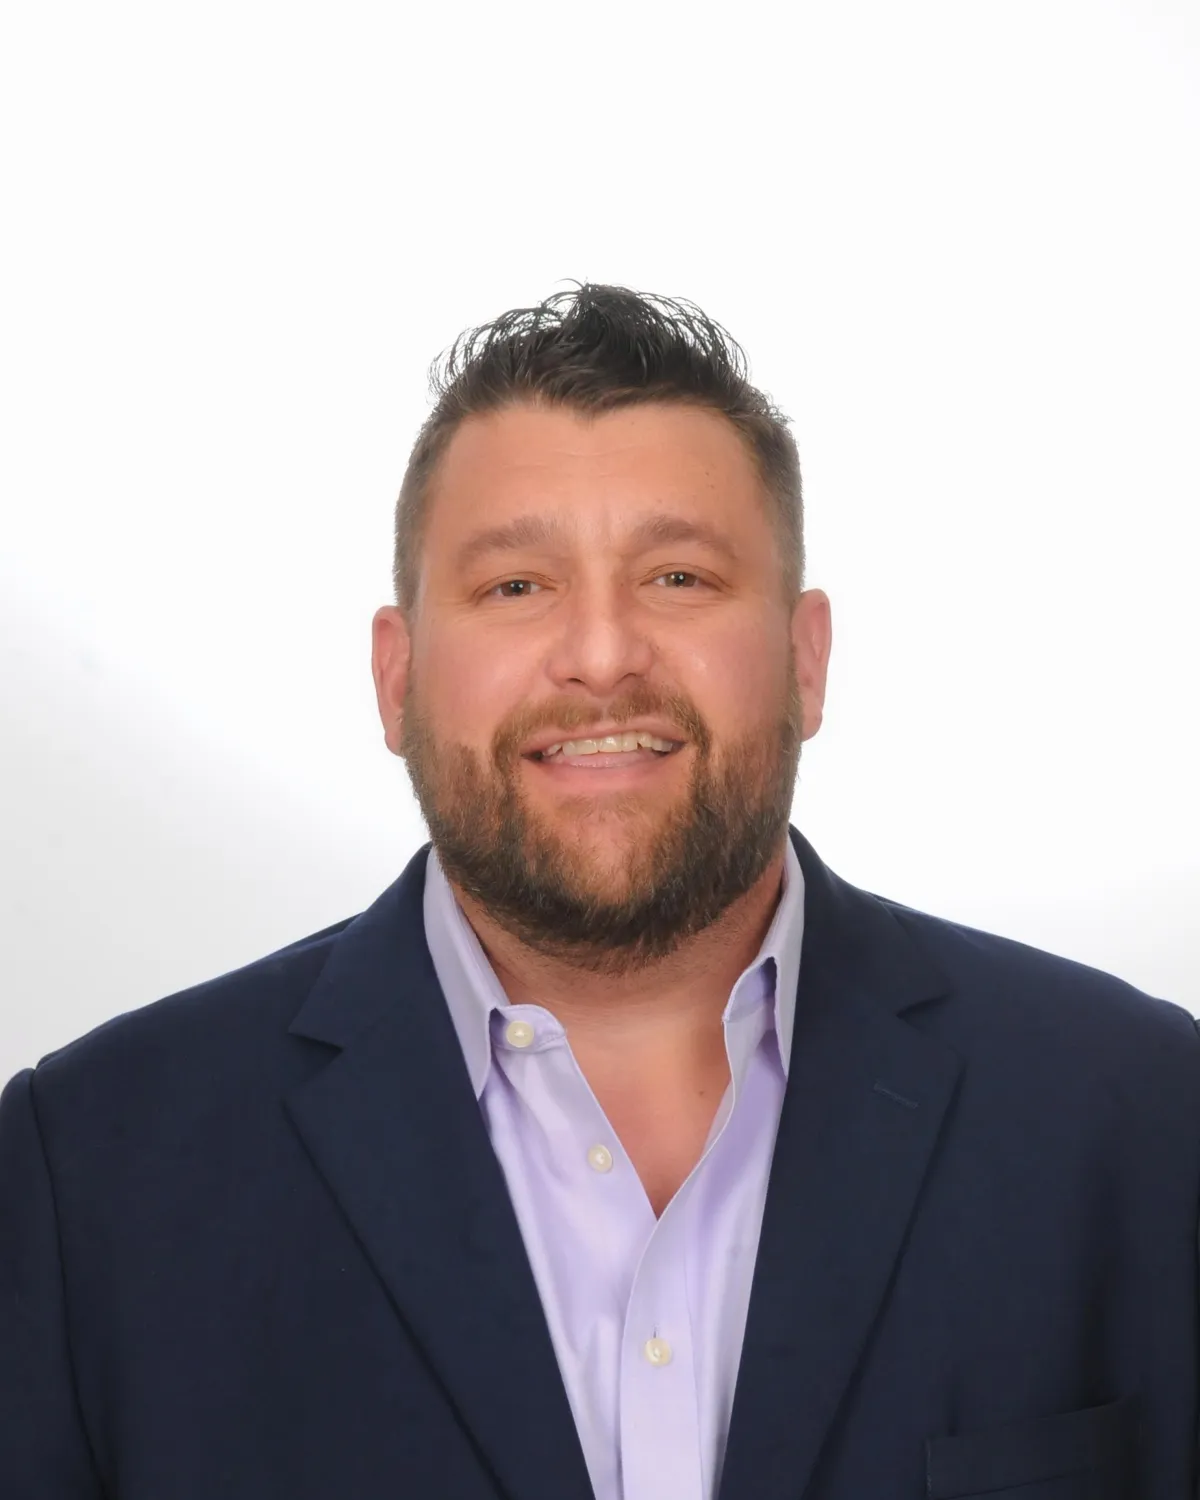
Bill Rapp, Mortgage Originator: NMLS 228246
"Brokers Are Better.
Better Pricing, Better Service!"
Subscribe To My List Below To Get Your Mortgage Quote Now!
Simply enter your name and email below:
WITH PROVEN STRATEGIES & PROVEN RESULTS
HERE'S WHAT MY CLIENTS SAY:
What People Are Saying:
Excellent Service
Bill is an exceptional loan officer. He helped us to purchase our home with very personal and professional service. He helped us navigate the whole process from start to closing without any problems. We didn't think we're qualified to purchase a house, but Bill went above and beyond to find a way to help us achieve our goal. He always responded very quickly with our requests, he would come back with different options with comparison chart to clearly indicate how much we need for down payment, monthly payments, interest rates, closing costs etc.
We would highly recommend Bill to anyone in need of lending services. In fact, we have already recommended Bill to one of our friends on purchasing a house.
--- David Chan - Houston, TX
Bank Statement Lending!
William Rapp of Network Funding, L. P. was very professional and I felt comfortable in dealing with him. I will definitely recommend him to family and friends.
--- Ian F - Missouri City, TX
Professionalism - Expert In Home Style Loan
Bill is an expert in the topic, his explanations and online material make a difference and he is always there from the beginning to the end. He is committed to make thing happen.
--- Felipe Caldern & Carolina Angel Gutierrez
Great Service!
Bill Rapp's handling of our loan (even though out of state) was unparalleled to any service I have been through prior, including 3 different real estate transactions and multiple refinances. Extremely quick close, with great options and flexibility for my families needs. All around A+
--- Chris & Beth Sheehan - San Jose, CA
Knowledgeable and Responsive!
Bill was a pleasure to work with and he made the loan process fairly easy. He answered all questions I had very quickly and was straight forward in doing it. I would recommend Bill to others.
--- Wes Brady - Richmond, TX
Very professional and always returned our calls!
Bill takes a lot of pride in his job and is very dependable. They were very patient and understanding. He went out of his way and explained all my questions and concerns. They were very professional and returned my phone calls and emails. He did a great job and I fully recommend him.
--- Therese, Malcom & Shirley Teixeira - Katy, TX
Great Job!
Bill helped us out from beginning to end of loan process. The loan closed in a timely manner as Bill worked hard with bank to get our to the final steps.
--- Kamal & Theresa Wilson - Hartford, CT
Avid Problem-Solver and Absolute Pleasure to Work With!
Bill Rapp worked very hard to ensure that we closed our loan and were able to move into our new home. He always had alternatives to any problems we encountered while closing. He worked with us from the beginning identifying solutions to any problems that we were having. He was an absolute pleasure to work with!
--- Nikita Rayani & Sanit Tejani - Houston, TX
Awesome to work with!
Being a first-time buyer I came in with lots of questions and concerns. Bill was always available for any questions I had and answered everything to my satisfaction. Bill made the loan process so painless that I could still concentrate on other things. We ended up closing early which made things even better. If you are in need of a lender and want someone who is very approachable and stays on top of your loan then Bill is your guy.
--- Cesar Raya - Richmond, TX
Loan Declined by my bank, and he saved the day!
Bill, did an amazing job helping me close on my house. He took the reigns and reassured me the best route to take to help close. He was accountable, thorough and trustworthy. I will continue to work with Network Funding, L.P. when it comes to home buying in the future because of the quality of service Bill gave.
--- Jacob Smith - Boerne, TX
Bill Rapp Will Definitely Make It Happen!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Corinne Wilson - Roselle, NJ
Knowledgeable, Honest, Trustworthy, and Reliable!
"I will definitely keep you in mind. If anyone I know needs financing, I will send them your way!"
--- Jon & Andrea Saleem, CRPC Financial Advisor - Houston, TX
Best Dam Mortgage Guy a man could know!
"Hands down the best loan experience to date!"
--- Gabe & Chelsea Jackson - Pearland, TX
Phenomenal, Hard Working and Never Quits!
Had a stupid foreclosure that could have been avoided if ex’s attny would have sent my buy out offer. So Bill was able to push this through with a 4 year foreclosure. He worked his butt off, was very diligent with his communication; and was very professional talking to me even when I was screaming and/or crying at him. Highly recommend this lender. He really go to the ends of the earth to help you!
--- Liz Keeter - Harlingen, TX
Exceptional customer service!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Isha Lopez & Mauricio Garcia - Houston, TX
Service with a capitol S
Bill went above and beyond at every turn. He worked late on Saturday, he worked late all the time. We wanted to close ASAP and he really helped make it happen for us.
--- Jeff & Wendy Heger - Houston, TX
Best Buying Experience!
I would would highly recommend going with Network Funding LP. As a first time home buyer I didn't know what to expect. Bill Rapp was very helpful in answering all my questions and guided me through all ghe steps. I couldn't have asked for a better buying experience!
--- Tabitha Turner - Humble, TX
Would recommend him and use him again!
Very involved and professional . Kept me informed and up to date on everything that was going on Went with me closing and was very helpful and knowledgeable.
--- Kathy Ward - Houston, TX
Great experience!
Well I meet bill back in December 2016 he got recommended by my real estate agent we had a house in sight and started the process to get approved but we fail due to my work history and credit bill told me not to give up and put me in contact with a credit repair company they help me bring my score up and bill walk me thru the process of getting a new line so this time around we got approved before looking for our house after we found it we still had a couple of hick up but with bills help on Sunday 6-18-17 to be exact Father's Day bill called me to give me the great news that we had got approved and the closing date was as scheduled bill was more than just a lender to my family he became a friend and I'm alway going to have him in mind for any other financial situation.
--- Alejandres Felimon - Richmond, TX
I really liked his attitude!
I wouldn't usually say this but the way he had handled my mortgage was really pleasant. I personally enjoyed the time spent with him while we discussed feasible rates. He's a great man with a great personality and he offered really low interests as well. Definitely recommend him to others.
--- Tom Troiano - Atlantic City, NJ
He's nothing short of a miracle!
I'm a self-employed businessman and had him figure out the mortgage of the house after 30% down payment. The interest rates I received were incredibly low given what I had thought of earlier. One other important thing to note was that I hadn't really taken any loans earlier, so I had no credit history. He helped me out with all that as well so I can't really call him anything else but a miracle.
--- Fran Suarez - Cleveland, OH
He's really helpful!
I made a bid to him and the very same day he gave me an offer which I couldn't resist. It was too intimidating with those incredibly low interest rates and all, thoroughly recommend him.
--- Kenny Mickle - Houston, TX
Expeditious!
Bill was very expeditious and made it real easy going through the loan process. I felt he was on top of things.
I deal with investment properties and will more than likely call on him again.
--- Wayne King - Pensacola, FL
Bill was great!
Bill made us feel like a friend all the way thru the process. He was patient and explained everything he needed clearly. He was available ANYTIME we had questions or needed more information. Hopefully we won’t go thru this process again anytime soon, but if we do - we’d choose Bill! =)
--- Barbra & Nick Grimmer - Austin, TX
Great broker!
Bill was a great broker to work with. As first time home buyers we had many questions about the process, Bill took the time to help us even calling us back on weekends with answers. I would not hesitate to recommend him to anyone looking for a broker to work with.
--- Murray & Lisa Turner - Pensacola, FL
Outstanding service!
I couldn't have been more pleased with Bill's level of service. He made what is typically a lengthy, arduous process far quicker and easier at every turn. I'm extremely comfortable recommending Bill to friends and family, and will definitely utilize his services again!
--- Jim Lipari - Austin, TX
Renovation Mortgage Specialist
Two little-known home renovation mortgage programs offer solutions for buyers and homeowners who want to renovate.
Fannie Mae and the Federal Housing Administration have home renovation mortgage programs that allow buyers to borrow based on what the house is expected to be worth after the home rehab is completed. Homeowners can also use both programs to refinance their existing mortgage plus the renovation costs into one loan.
FHA's 203(k) program and Fannie's HomeStyle Renovation Mortgage have been around for years. In the old days -- when most borrowers could easily get second mortgages or generous credit lines to pay for renovations -- these loans weren't as appealing as they are today.
Home renovation loans are in Demand !
"A couple years ago, there wasn't as much demand for these loans," says Bill Rapp, a senior loan originator with Network Funding in Houston, who specializes in renovation mortgages. Demand surged in the aftermath of the housing crisis, when borrowers saw them as a way to buy and renovate distressed properties.
How it works Unlike credit lines, these renovation loans require borrowers to show that the money was spent on the house. In the standard FHA 203(k) program, the borrower hires a consultant to assess the construction plan and to perform an inspection before each draw is made. A "draw" happens when a portion of the money is disbursed to the contractor. Borrowers have up to six months to finish the project and are allowed up to five draws. The HomeStyle program does not require a consultant to monitor the work, only an initial and final inspection.
Great for foreclosure hunters !
While rehab loans involve more work than traditional mortgages, they can be a great tool for those who want to buy discounted homes that need repair.
Bill Rapp says he helped a couple who bought a foreclosed house in Houston, TX for $26,000 and borrowed $136,000 to renovate the property. An appraisal estimated the home would be worth about $135,000 after the work was completed. The couple was able to take out an FHA 203(k) mortgage totaling $144,000, which covered the price of the house, renovations, and loan costs, minus a down payment.
But how do you know which loan is best? It depends on the situation.
203(k) vs. HomeStyle .
Those who don't have great credit should probably opt for an FHA 203(k). Most Fannie Mae HomeStyle lenders require a credit score above 660. To get the best rate on a HomeStyle mortgage, borrowers need to have a minimum 740 credit score, Bill Rapp says.
"If you have a 740 score and 10 percent down, a HomeStyle is definitely cheaper," she says. That's because FHA mortgages carry higher mortgage insurance premiums for borrowers who put the least amount down. FHA 203(k) home renovation mortgages have an upfront fee that is rolled into the loan amount. Less-than-stellar credit For borrowers with credit scores lower than 740, it's best to compare estimates, Bill Rapp says.
FHA does not set a minimum score requirement for 203(k) loans, but many lenders require a score of 640 or greater. There are a few exceptions, and some lenders accept scores as low as 580, Bill Rapp says.
Under the FHA's 203(k) program, borrowers can get a mortgage with a down payment as little as 3.5 percent. HomeStyle requires a minimum 5 percent down payment.
The FHA 203(k) program is available only for owner-occupants. The HomeStyle program allows investors.
How much do you need?
Another key factor a borrower should consider when deciding whether to go with a 203(k) or a HomeStyle home renovation mortgage is the size of the loan.
The 203(k) rehab mortgage has to comply with FHA loan limits. The limit varies by county but is $314,827 in most places. In high-cost areas, the limit is as high as $765,525.
You may be able to borrow more with the 203(k) than with HomeStyle if you are borrowing up to the local loan limit.
With a 203(k) loan, borrowers can get up to 110 percent of the home's appraised value, compared with 95 percent with a HomeStyle loan. Both appraisals are based on what the house is expected to be worth after repairs.
What do you want to fix?
FHA's 203(k) rehab loan does not allow borrowers to use the money for luxury items such as adding a swimming pool or a spa, but HomeStyle does.
Borrowers can opt for a streamline FHA 203(k) home rehabilitation loan if they need less than $35,000 and don't have to do any structural repairs or major landscaping work. The streamline 203(k) is similar to a standard 203(k) but is easier to get and involves less paperwork and less bureaucracy, Bill Rapp says. Streamline loans don't require the borrower to hire a consultant.
Call Bill Rapp, The Mortgage Viking, today to discuss your options 281-222-0433.
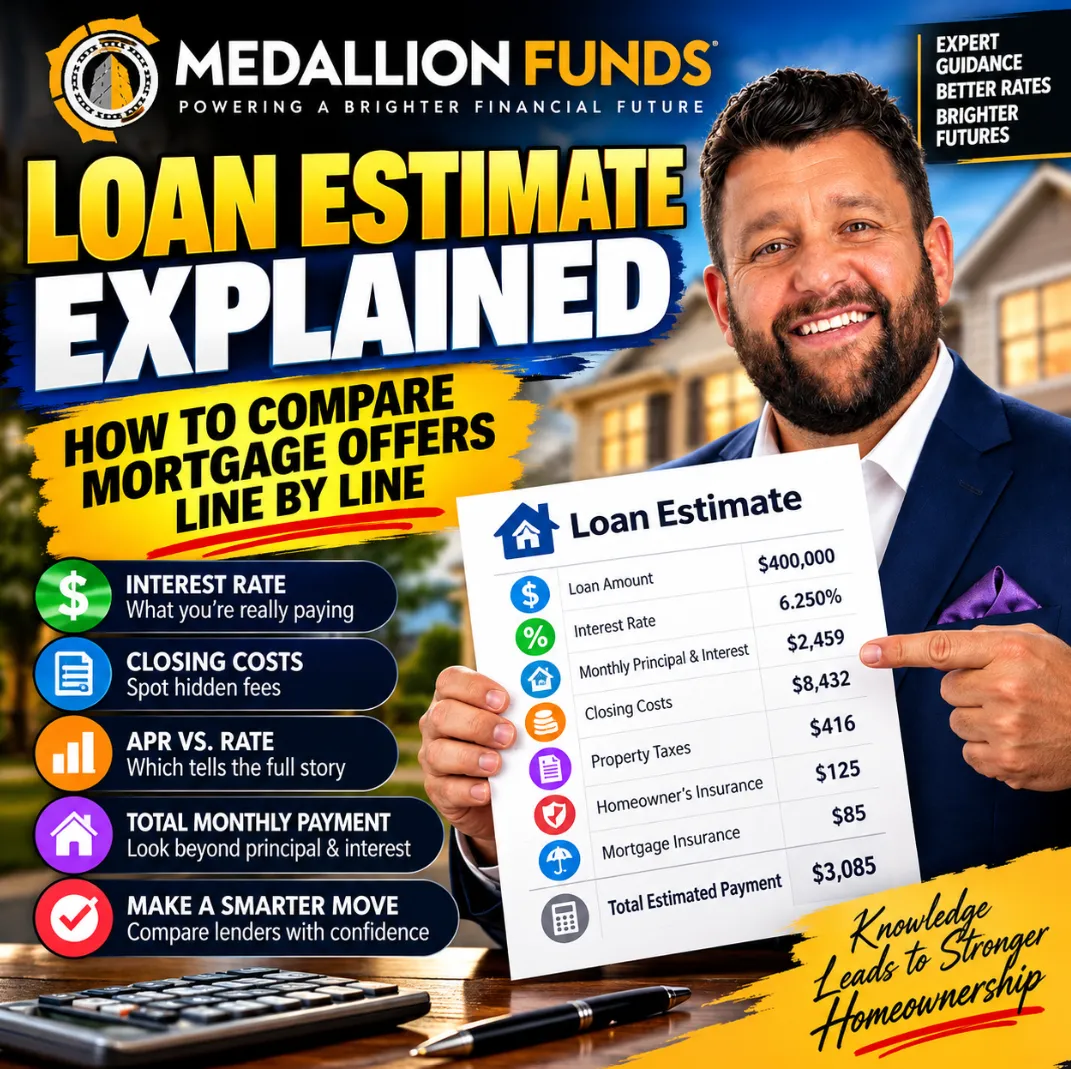
🏡 Loan Estimate Explained: How to Compare Mortgage Offers Line by Line and Avoid Costly Mistakes 💰
🏡 Loan Estimate Explained: How to Compare Mortgage Offers Line by Line and Avoid Costly Mistakes 💰
🔍 Mortgage Loan Estimate Guide: 7 Things to Compare Before Choosing a Lender 🏦
______________________________________________________________________________
Loan Estimate Explained: How to Compare Mortgage Offers Line by Line and Avoid Costly Mistakes
By Bill Rapp, CCIM | Director of Capital Advisory | Medallion Funds
You applied for a mortgage, received offers from two or three lenders, and now you're staring at pages of numbers.
One lender advertises a lower interest rate. Another promises lower closing costs. A third claims to offer the best overall deal.
How do you know which mortgage offer actually saves you money?
The answer starts with understanding your Loan Estimate.
A Loan Estimate is a standardized, three-page mortgage disclosure designed to help borrowers understand the costs, terms, and risks associated with a proposed home loan.
But here's something many homebuyers don't realize:
The lender offering the lowest interest rate isn't necessarily offering the least expensive mortgage.
At Medallion Funds, we help borrowers evaluate mortgage financing based on the complete loan structure—not just the advertised interest rate.
Let's break down how to read a Loan Estimate, compare mortgage lenders, and identify costs that could make one offer significantly more expensive than another.
What Is a Mortgage Loan Estimate?
A Loan Estimate is a standardized document that lenders generally must provide within three business days after receiving the six pieces of information that constitute a mortgage application under federal disclosure rules.
Those six pieces are:
1.Your name
2.Your income
3.Your Social Security number to obtain a credit report
4.The property address
5.An estimate of the property's value
6.The mortgage loan amount requested
This requirement applies to most closed-end consumer mortgages, although certain loan types and transactions are exempt.
The Loan Estimate provides information about:
·Loan amount and interest rate
·Monthly principal and interest payment
·Estimated property taxes and insurance
·Mortgage insurance, when applicable
·Origination charges and discount points
·Third-party closing costs
·Estimated cash needed to close
·Whether the rate is locked
·Important loan features and potential risks
The purpose is simple: give borrowers a consistent framework for comparing mortgage offers before committing to a lender.
However, receiving a Loan Estimate does not mean your mortgage has been approved, and the document is not a guarantee that every estimated cost will remain unchanged.
Page 1: Understand the Mortgage You're Being Offered
The first page of your Loan Estimate summarizes the most important terms of your proposed mortgage.
1. Loan Amount
The loan amount is the amount you're borrowing, not necessarily the home's purchase price.
For example:
Item | Amount |
Purchase price | $400,000 |
Down payment (10%) | $40,000 |
Mortgage loan amount | $360,000 |
When comparing lenders, make sure each offer uses the same loan amount and down payment assumptions.
Otherwise, you're not comparing equivalent financing options.
2. Interest Rate
Your mortgage interest rate determines how much interest accrues on the outstanding loan balance.
A lower interest rate generally means a lower principal and interest payment, assuming the same loan amount, loan type, and repayment term.
But a lower rate can come with higher upfront costs.
One lender might offer a 6.25% interest rate with $5,000 in discount points, while another offers 6.50% with no points.
Which is better?
That depends on how long you expect to keep the mortgage and how much money you want to spend upfront.
We'll examine that calculation shortly.
3. Monthly Principal and Interest
Your principal and interest payment is the amount required to repay the borrowed funds and the associated interest.
It does not necessarily represent your total monthly housing expense.
Your actual monthly housing budget may also include:
·Property taxes
·Homeowners insurance
·Mortgage insurance
·HOA dues
·Flood insurance, when applicable
Important: HOA dues are generally not included in the lender's estimated total monthly payment on the Loan Estimate, even though they can significantly affect your household budget.
4. Projected Payments
The Projected Payments section shows how your payment may change over time.
Pay particular attention to:
·Adjustable-rate mortgage adjustments
·Mortgage insurance changes
·Escrow assumptions
·Potential increases in taxes and insurance
If you're comparing a fixed-rate mortgage with an adjustable-rate mortgage, don't focus exclusively on the initial payment.
Evaluate how the payment could change after the introductory period ends.
5. Estimated Taxes, Insurance, and Assessments
This section provides an estimate of additional housing expenses.
For Texas homebuyers, property taxes can represent a substantial portion of the monthly housing budget.
Also remember that property taxes and insurance premiums can change after closing.
A mortgage that looks affordable based on principal and interest alone may become uncomfortable once the full housing expense is included.
Page 2: Compare Closing Costs Line by Line
Page 2 is where mortgage comparisons become particularly valuable.
It provides a breakdown of estimated closing costs, including lender charges, third-party services, and prepaid expenses.
Understanding these categories helps you distinguish between costs controlled by the lender and costs that may be similar regardless of which lender you choose.
Section A: Origination Charges
This section typically includes lender-controlled charges such as:
·Origination fees
·Underwriting or processing charges
·Discount points
Discount points are upfront charges paid to obtain a particular interest rate. One point equals 1% of the loan amount, although the interest-rate reduction associated with a point varies.
For example, on a $360,000 mortgage:
One discount point = $3,600.
Two lenders can advertise the same rate while charging different origination fees.
That's why comparing interest rates alone can be misleading.
Section B: Services You Cannot Shop For
These are services for which the lender generally selects the provider.
Examples may include:
·Appraisal
·Credit report
·Flood determination
·Certain tax monitoring services
The borrower typically cannot select alternative providers for these particular services.
Section C: Services You Can Shop For
This section identifies services for which the borrower may select a provider, subject to the applicable disclosure rules.
Depending on the transaction, these may include:
·Title services
·Settlement or closing services
·Survey
·Pest inspection
Shopping for eligible services may reduce closing costs.
However, the availability of providers and any applicable fee limits depend on the transaction and the lender's written provider list.
Section E: Taxes and Other Government Fees
These charges can include:
·Recording fees
·Transfer taxes, where applicable
These costs are generally tied to the transaction and jurisdiction rather than the lender's pricing.
Section F: Prepaids
Prepaid expenses may include:
·Homeowners insurance premiums
·Prepaid mortgage interest
·Property taxes
·Mortgage insurance premiums, when applicable
These expenses are not necessarily lender fees.
For example, prepaid interest can vary depending on the closing date.
Section G: Initial Escrow Payment at Closing
Lenders may collect funds to establish an escrow account for future tax and insurance payments.
The amount can vary based on payment schedules, closing dates, and escrow requirements.
A higher escrow deposit doesn't automatically mean a lender is more expensive.
It may simply reflect a different estimate of taxes, insurance, or the timing of upcoming bills.
Section H: Other Costs
Other costs may include optional or transaction-specific expenses, such as:
·Owner's title insurance
·Home warranty
·Certain inspections
·Real estate-related fees
These charges should be reviewed individually to determine whether they are required, optional, or negotiable.
Page 3: Find the Real Cost of the Mortgage
Page 3 contains some of the most useful information for comparing competing mortgage offers.
Annual Percentage Rate (APR)
The annual percentage rate, or APR, incorporates the interest rate and certain finance charges into a standardized annualized measure of borrowing cost.
The APR is typically higher than the note rate when applicable finance charges are included.
For comparable fixed-rate mortgages, APR can help reveal the impact of upfront borrowing costs.
However, APR is not a complete measure of the best loan for your circumstances.
For example, an adjustable-rate mortgage's APR relies on assumptions about future rate changes. A loan with a lower APR may also require more cash upfront or have a less favorable short-term break-even point.
Total Interest Percentage (TIP)
The Total Interest Percentage estimates the total interest paid over the scheduled loan term as a percentage of the original loan amount.
For example, a TIP of 95% indicates that total scheduled interest would equal approximately 95% of the original loan amount if the loan is paid according to its terms.
TIP is useful for understanding long-term interest expense, but it does not predict your actual interest expense if you sell, refinance, or make additional principal payments.
In 5 Years Comparison
One of the most useful sections on Page 3 is the Comparisons box.
It shows:
·The total amount you will have paid in five years
·The amount of principal you will have paid off in five years
This allows you to evaluate how much money is spent and how much loan balance is reduced during the same period.
For homebuyers who may relocate, refinance, or sell within several years, this comparison can be especially valuable.
Real Example: Comparing Two Mortgage Offers
Let's assume you're purchasing a $400,000 home with a $360,000 mortgage.
You receive two hypothetical 30-year fixed-rate offers:
Loan Feature | Lender A | Lender B |
Loan amount | $360,000 | $360,000 |
Interest rate | 6.25% | 6.50% |
Discount points | $5,000 | $0 |
Monthly principal & interest | $2,217 | $2,275 |
Approximate monthly savings with A | $58 | — |
Payments are rounded, illustrative calculations and exclude taxes, insurance, and other costs. Both offers assume the same loan amount, term, and all other charges.
Lender A saves approximately $58 per month.
However, Lender A requires an additional $5,000 upfront.
A simple payment-savings calculation gives us:
$5,000 ÷ $58 = approximately 86 months.
That's roughly 7.2 years.
This simplified break-even calculation suggests it could take more than seven years of lower monthly payments to recover the additional upfront cost.
The true economic comparison is more nuanced because the two loans amortize at different rates. A full analysis should consider the remaining principal balances, the time value of money, and any applicable tax consequences.
If you expect to refinance or sell within three years, paying the additional points may not make financial sense.
If you expect to keep the loan much longer, the lower rate could be worthwhile.
The best mortgage isn't always the one with the lowest rate. It's the one that fits your expected ownership period, cash position, and financial objectives.
How to Compare Mortgage Loan Estimates Correctly
Before selecting a lender, request Loan Estimates based on equivalent assumptions.
Use this checklist:
1.Same loan amount: Verify the borrowed amount matches across offers.
2.Same loan program: Compare conventional to conventional, FHA to FHA, or VA to VA before evaluating cross-program tradeoffs.
3.Same loan term: A 15-year mortgage is not directly comparable to a 30-year mortgage.
4.Same rate-lock status: Confirm whether the interest rate is locked and the lock expiration date.
5.Same discount-point assumptions: Determine how much you're paying upfront for the advertised rate.
6.Same property and insurance assumptions: Check taxes, homeowners insurance, mortgage insurance, and escrow estimates.
7.Same lender-credit treatment: Review any credits that offset closing costs.
8.Same comparison date: Mortgage pricing can change, so obtain quotes as close together in time as practical.
You should also review the Estimated Cash to Close section carefully.
This is the estimated amount you need to bring to closing after accounting for the down payment, closing costs, deposits, credits, and other adjustments.
Can Closing Costs Change After Receiving a Loan Estimate?
Yes, but different categories of charges are subject to different rules.
Some charges generally cannot increase from the original estimate unless a permitted exception applies.
Other charges may be subject to a cumulative 10% tolerance.
Still others, such as certain prepaid expenses and services selected independently by the borrower, may change without a numerical tolerance limit, provided the original estimates were made in good faith.
A valid changed circumstance, rate-lock event, or other permitted reason may also allow the lender to issue a revised Loan Estimate.
The important takeaway is that not every fee is guaranteed to stay the same, but lenders cannot simply increase regulated charges without regard to federal disclosure requirements.
Before closing, you'll receive a Closing Disclosure that provides the final terms and costs. For most covered mortgages, you must receive it at least three business days before consummation.
Compare the Closing Disclosure against your latest Loan Estimate and ask about any unexpected changes.
Why Working With a Mortgage Broker Can Help
When you approach a single bank, you're generally reviewing that institution's available mortgage products and pricing.
A mortgage broker can help you explore financing options from multiple wholesale lending sources, depending on program availability and eligibility.
At Medallion Funds, our objective is to help borrowers understand the tradeoffs between:
·Interest rates and discount points
·Monthly payments and upfront costs
·Fixed-rate and adjustable-rate financing
·Conventional, FHA, VA, jumbo, and eligible specialty programs
·Cash-to-close requirements
·Long-term costs and refinancing considerations
We also work with self-employed borrowers, medical professionals, real estate investors, and borrowers who may benefit from alternative mortgage qualification programs.
Not every program is suitable for every borrower, and not every specialty or investment loan uses the standard consumer Loan Estimate.
The goal is to match the financing structure to the borrower's actual needs.
Frequently Asked Questions About Loan Estimates
Is a Loan Estimate a mortgage approval?
No. A Loan Estimate is a disclosure of proposed loan terms and estimated costs. Final approval depends on underwriting, property evaluation, documentation, and other lender requirements.
Can I get Loan Estimates from multiple lenders?
Yes. Comparing offers from multiple lenders is one of the most effective ways to evaluate mortgage pricing.
Does receiving a Loan Estimate mean my interest rate is locked?
No. Check the rate-lock section on Page 1. A disclosed rate is not necessarily locked.
Is the lender with the lowest APR always the best choice?
Not necessarily. APR is a useful comparison tool, but you should also evaluate upfront costs, monthly payments, loan features, and how long you expect to keep the mortgage.
What are mortgage discount points?
Discount points are upfront charges associated with obtaining a particular mortgage rate. One point equals 1% of the loan amount.
Can I negotiate mortgage closing costs?
Some charges may be negotiable or offset through lender credits, seller concessions, or provider shopping, subject to loan program rules and transaction limitations.
What's the difference between a Loan Estimate and a Closing Disclosure?
The Loan Estimate provides proposed terms and estimated costs early in the process. The Closing Disclosure provides the final loan terms and closing costs before consummation.
Final Thoughts: Compare the Entire Mortgage, Not Just the Rate
Choosing a mortgage is one of the most important financial decisions you'll make as a homebuyer.
A difference of a few thousand dollars in closing costs or a fraction of a percentage point in interest rate can have a meaningful impact on your finances.
Before accepting a mortgage offer, ask:
What's my total cash to close? How much will I pay every month? What does this loan cost over the time I expect to keep it?
Those questions are far more useful than simply asking which lender advertises the lowest interest rate.
Let's Review Your Mortgage Options
I'm Bill Rapp, CCIM, Director of Capital Advisory with Medallion Funds.
Whether you're purchasing your first home, moving into a larger property, refinancing, or exploring specialized mortgage programs, I can help you evaluate financing options and understand the numbers.
Reference for consumer disclosure rules: Consumer Financial Protection Bureau, Loan Estimate resources and Closing Disclosure resources.
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
Main Office:
Medallion Funds
[email protected]
11920 Southern Highlands PKWY Suite 302Las Vegas, NV 89141
Texas Complaint and Recovery Fund Notice
All Rights Reserved Copyright © 2021 - Bill Rapp The Mortgage Viking | NMLS #228246