ATTENTION: For Those who are serious about Getting Pre-Qualified FAST!
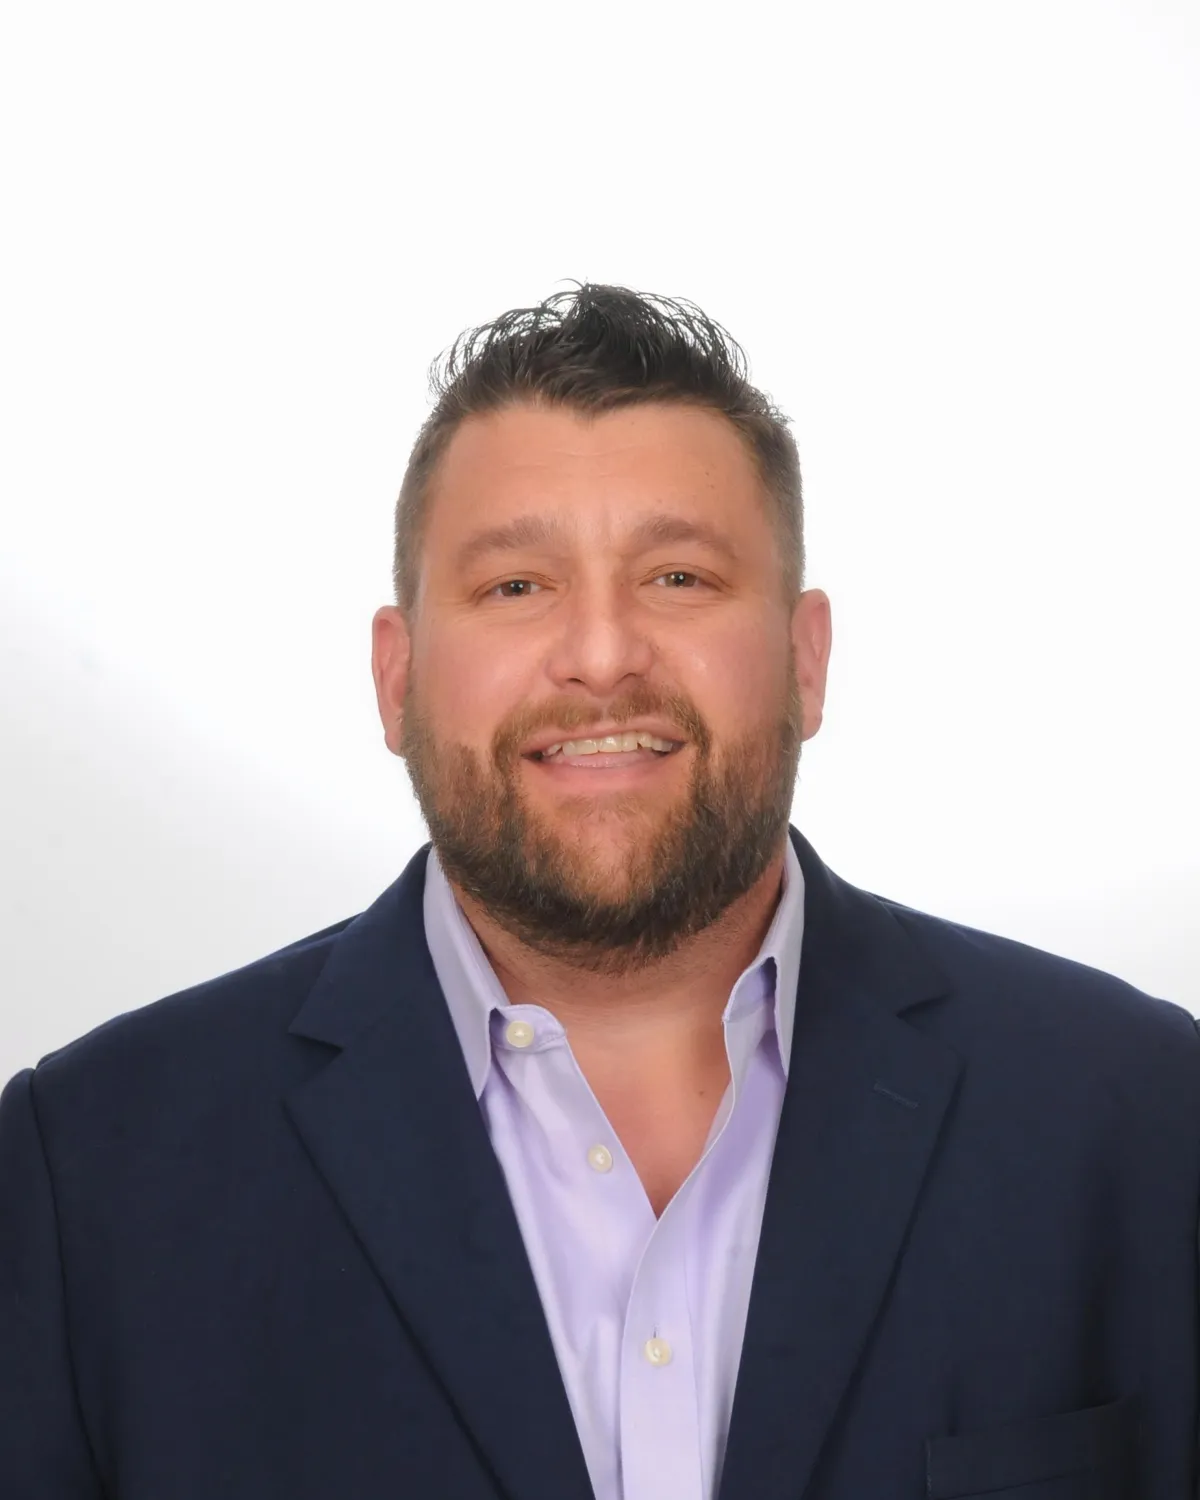
Bill Rapp, Mortgage Originator: NMLS 228246
"Brokers Are Better.
Better Pricing, Better Service!"
Subscribe To My List Below To Get Your Mortgage Quote Now!
Simply enter your name and email below:
WITH PROVEN STRATEGIES & PROVEN RESULTS
HERE'S WHAT MY CLIENTS SAY:
What People Are Saying:
Excellent Service
Bill is an exceptional loan officer. He helped us to purchase our home with very personal and professional service. He helped us navigate the whole process from start to closing without any problems. We didn't think we're qualified to purchase a house, but Bill went above and beyond to find a way to help us achieve our goal. He always responded very quickly with our requests, he would come back with different options with comparison chart to clearly indicate how much we need for down payment, monthly payments, interest rates, closing costs etc.
We would highly recommend Bill to anyone in need of lending services. In fact, we have already recommended Bill to one of our friends on purchasing a house.
--- David Chan - Houston, TX
Bank Statement Lending!
William Rapp of Network Funding, L. P. was very professional and I felt comfortable in dealing with him. I will definitely recommend him to family and friends.
--- Ian F - Missouri City, TX
Professionalism - Expert In Home Style Loan
Bill is an expert in the topic, his explanations and online material make a difference and he is always there from the beginning to the end. He is committed to make thing happen.
--- Felipe Caldern & Carolina Angel Gutierrez
Great Service!
Bill Rapp's handling of our loan (even though out of state) was unparalleled to any service I have been through prior, including 3 different real estate transactions and multiple refinances. Extremely quick close, with great options and flexibility for my families needs. All around A+
--- Chris & Beth Sheehan - San Jose, CA
Knowledgeable and Responsive!
Bill was a pleasure to work with and he made the loan process fairly easy. He answered all questions I had very quickly and was straight forward in doing it. I would recommend Bill to others.
--- Wes Brady - Richmond, TX
Very professional and always returned our calls!
Bill takes a lot of pride in his job and is very dependable. They were very patient and understanding. He went out of his way and explained all my questions and concerns. They were very professional and returned my phone calls and emails. He did a great job and I fully recommend him.
--- Therese, Malcom & Shirley Teixeira - Katy, TX
Great Job!
Bill helped us out from beginning to end of loan process. The loan closed in a timely manner as Bill worked hard with bank to get our to the final steps.
--- Kamal & Theresa Wilson - Hartford, CT
Avid Problem-Solver and Absolute Pleasure to Work With!
Bill Rapp worked very hard to ensure that we closed our loan and were able to move into our new home. He always had alternatives to any problems we encountered while closing. He worked with us from the beginning identifying solutions to any problems that we were having. He was an absolute pleasure to work with!
--- Nikita Rayani & Sanit Tejani - Houston, TX
Awesome to work with!
Being a first-time buyer I came in with lots of questions and concerns. Bill was always available for any questions I had and answered everything to my satisfaction. Bill made the loan process so painless that I could still concentrate on other things. We ended up closing early which made things even better. If you are in need of a lender and want someone who is very approachable and stays on top of your loan then Bill is your guy.
--- Cesar Raya - Richmond, TX
Loan Declined by my bank, and he saved the day!
Bill, did an amazing job helping me close on my house. He took the reigns and reassured me the best route to take to help close. He was accountable, thorough and trustworthy. I will continue to work with Network Funding, L.P. when it comes to home buying in the future because of the quality of service Bill gave.
--- Jacob Smith - Boerne, TX
Bill Rapp Will Definitely Make It Happen!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Corinne Wilson - Roselle, NJ
Knowledgeable, Honest, Trustworthy, and Reliable!
"I will definitely keep you in mind. If anyone I know needs financing, I will send them your way!"
--- Jon & Andrea Saleem, CRPC Financial Advisor - Houston, TX
Best Dam Mortgage Guy a man could know!
"Hands down the best loan experience to date!"
--- Gabe & Chelsea Jackson - Pearland, TX
Phenomenal, Hard Working and Never Quits!
Had a stupid foreclosure that could have been avoided if ex’s attny would have sent my buy out offer. So Bill was able to push this through with a 4 year foreclosure. He worked his butt off, was very diligent with his communication; and was very professional talking to me even when I was screaming and/or crying at him. Highly recommend this lender. He really go to the ends of the earth to help you!
--- Liz Keeter - Harlingen, TX
Exceptional customer service!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Isha Lopez & Mauricio Garcia - Houston, TX
Service with a capitol S
Bill went above and beyond at every turn. He worked late on Saturday, he worked late all the time. We wanted to close ASAP and he really helped make it happen for us.
--- Jeff & Wendy Heger - Houston, TX
Best Buying Experience!
I would would highly recommend going with Network Funding LP. As a first time home buyer I didn't know what to expect. Bill Rapp was very helpful in answering all my questions and guided me through all ghe steps. I couldn't have asked for a better buying experience!
--- Tabitha Turner - Humble, TX
Would recommend him and use him again!
Very involved and professional . Kept me informed and up to date on everything that was going on Went with me closing and was very helpful and knowledgeable.
--- Kathy Ward - Houston, TX
Great experience!
Well I meet bill back in December 2016 he got recommended by my real estate agent we had a house in sight and started the process to get approved but we fail due to my work history and credit bill told me not to give up and put me in contact with a credit repair company they help me bring my score up and bill walk me thru the process of getting a new line so this time around we got approved before looking for our house after we found it we still had a couple of hick up but with bills help on Sunday 6-18-17 to be exact Father's Day bill called me to give me the great news that we had got approved and the closing date was as scheduled bill was more than just a lender to my family he became a friend and I'm alway going to have him in mind for any other financial situation.
--- Alejandres Felimon - Richmond, TX
I really liked his attitude!
I wouldn't usually say this but the way he had handled my mortgage was really pleasant. I personally enjoyed the time spent with him while we discussed feasible rates. He's a great man with a great personality and he offered really low interests as well. Definitely recommend him to others.
--- Tom Troiano - Atlantic City, NJ
He's nothing short of a miracle!
I'm a self-employed businessman and had him figure out the mortgage of the house after 30% down payment. The interest rates I received were incredibly low given what I had thought of earlier. One other important thing to note was that I hadn't really taken any loans earlier, so I had no credit history. He helped me out with all that as well so I can't really call him anything else but a miracle.
--- Fran Suarez - Cleveland, OH
He's really helpful!
I made a bid to him and the very same day he gave me an offer which I couldn't resist. It was too intimidating with those incredibly low interest rates and all, thoroughly recommend him.
--- Kenny Mickle - Houston, TX
Expeditious!
Bill was very expeditious and made it real easy going through the loan process. I felt he was on top of things.
I deal with investment properties and will more than likely call on him again.
--- Wayne King - Pensacola, FL
Bill was great!
Bill made us feel like a friend all the way thru the process. He was patient and explained everything he needed clearly. He was available ANYTIME we had questions or needed more information. Hopefully we won’t go thru this process again anytime soon, but if we do - we’d choose Bill! =)
--- Barbra & Nick Grimmer - Austin, TX
Great broker!
Bill was a great broker to work with. As first time home buyers we had many questions about the process, Bill took the time to help us even calling us back on weekends with answers. I would not hesitate to recommend him to anyone looking for a broker to work with.
--- Murray & Lisa Turner - Pensacola, FL
Outstanding service!
I couldn't have been more pleased with Bill's level of service. He made what is typically a lengthy, arduous process far quicker and easier at every turn. I'm extremely comfortable recommending Bill to friends and family, and will definitely utilize his services again!
--- Jim Lipari - Austin, TX
Renovation Mortgage Specialist
Two little-known home renovation mortgage programs offer solutions for buyers and homeowners who want to renovate.
Fannie Mae and the Federal Housing Administration have home renovation mortgage programs that allow buyers to borrow based on what the house is expected to be worth after the home rehab is completed. Homeowners can also use both programs to refinance their existing mortgage plus the renovation costs into one loan.
FHA's 203(k) program and Fannie's HomeStyle Renovation Mortgage have been around for years. In the old days -- when most borrowers could easily get second mortgages or generous credit lines to pay for renovations -- these loans weren't as appealing as they are today.
Home renovation loans are in Demand !
"A couple years ago, there wasn't as much demand for these loans," says Bill Rapp, a senior loan originator with Network Funding in Houston, who specializes in renovation mortgages. Demand surged in the aftermath of the housing crisis, when borrowers saw them as a way to buy and renovate distressed properties.
How it works Unlike credit lines, these renovation loans require borrowers to show that the money was spent on the house. In the standard FHA 203(k) program, the borrower hires a consultant to assess the construction plan and to perform an inspection before each draw is made. A "draw" happens when a portion of the money is disbursed to the contractor. Borrowers have up to six months to finish the project and are allowed up to five draws. The HomeStyle program does not require a consultant to monitor the work, only an initial and final inspection.
Great for foreclosure hunters !
While rehab loans involve more work than traditional mortgages, they can be a great tool for those who want to buy discounted homes that need repair.
Bill Rapp says he helped a couple who bought a foreclosed house in Houston, TX for $26,000 and borrowed $136,000 to renovate the property. An appraisal estimated the home would be worth about $135,000 after the work was completed. The couple was able to take out an FHA 203(k) mortgage totaling $144,000, which covered the price of the house, renovations, and loan costs, minus a down payment.
But how do you know which loan is best? It depends on the situation.
203(k) vs. HomeStyle .
Those who don't have great credit should probably opt for an FHA 203(k). Most Fannie Mae HomeStyle lenders require a credit score above 660. To get the best rate on a HomeStyle mortgage, borrowers need to have a minimum 740 credit score, Bill Rapp says.
"If you have a 740 score and 10 percent down, a HomeStyle is definitely cheaper," she says. That's because FHA mortgages carry higher mortgage insurance premiums for borrowers who put the least amount down. FHA 203(k) home renovation mortgages have an upfront fee that is rolled into the loan amount. Less-than-stellar credit For borrowers with credit scores lower than 740, it's best to compare estimates, Bill Rapp says.
FHA does not set a minimum score requirement for 203(k) loans, but many lenders require a score of 640 or greater. There are a few exceptions, and some lenders accept scores as low as 580, Bill Rapp says.
Under the FHA's 203(k) program, borrowers can get a mortgage with a down payment as little as 3.5 percent. HomeStyle requires a minimum 5 percent down payment.
The FHA 203(k) program is available only for owner-occupants. The HomeStyle program allows investors.
How much do you need?
Another key factor a borrower should consider when deciding whether to go with a 203(k) or a HomeStyle home renovation mortgage is the size of the loan.
The 203(k) rehab mortgage has to comply with FHA loan limits. The limit varies by county but is $314,827 in most places. In high-cost areas, the limit is as high as $765,525.
You may be able to borrow more with the 203(k) than with HomeStyle if you are borrowing up to the local loan limit.
With a 203(k) loan, borrowers can get up to 110 percent of the home's appraised value, compared with 95 percent with a HomeStyle loan. Both appraisals are based on what the house is expected to be worth after repairs.
What do you want to fix?
FHA's 203(k) rehab loan does not allow borrowers to use the money for luxury items such as adding a swimming pool or a spa, but HomeStyle does.
Borrowers can opt for a streamline FHA 203(k) home rehabilitation loan if they need less than $35,000 and don't have to do any structural repairs or major landscaping work. The streamline 203(k) is similar to a standard 203(k) but is easier to get and involves less paperwork and less bureaucracy, Bill Rapp says. Streamline loans don't require the borrower to hire a consultant.
Call Bill Rapp, The Mortgage Viking, today to discuss your options 281-222-0433.
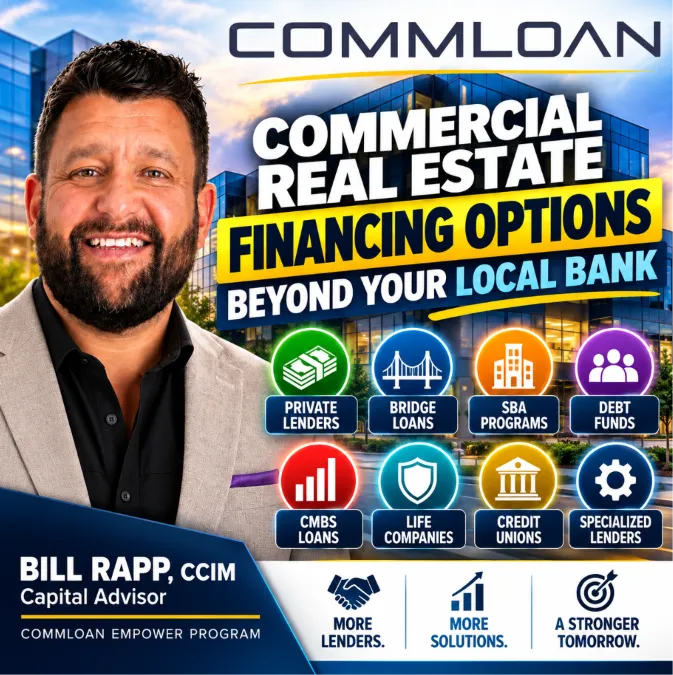
🏦 Commercial Real Estate Financing Options Beyond Your Local Bank: 7 Alternatives Every Investor Should Know 🚀
🏦 Commercial Real Estate Financing Options Beyond Your Local Bank: 7 Alternatives Every Investor Should Know 🚀
💰 Bank Said No? Discover Commercial Real Estate Financing Options That Could Save Your Next Deal! 🏢
________________________________________________________________________________
Your Local Bank Isn't Your Only Commercial Real Estate Financing Option
When most commercial real estate investors and business owners need financing, their first call is often to a local bank.
That makes sense. Community banks and regional financial institutions play an important role in commercial real estate lending. They understand their markets, develop long-term borrower relationships, and offer competitive financing for transactions that fit their lending guidelines.
But what happens when your bank says no?
What if your property doesn't meet its occupancy requirements? What if your loan request exceeds its lending limits? What if you need a bridge loan, a cash-out refinance, or financing for a specialized commercial property?
A bank decline doesn't necessarily mean your commercial real estate transaction is unfinanceable. It may mean you need a different lending strategy.
Today, commercial borrowers have access to financing solutions beyond traditional banks, including private lenders, debt funds, credit unions, SBA programs, CMBS lenders, life insurance companies, and specialized commercial mortgage lenders.
Understanding these alternatives can make the difference between losing an opportunity and successfully structuring your next commercial real estate transaction.
Why Traditional Banks Decline Commercial Real Estate Loans
Banks evaluate commercial real estate financing requests using internal credit policies, regulatory requirements, portfolio concentration limits, and risk management standards.
Even financially strong borrowers can receive a decline when a transaction falls outside a lender's credit box.
Common reasons include:
·Debt Service Coverage Ratio (DSCR): The property's net operating income may not sufficiently cover the proposed debt payments.
·Loan-to-Value (LTV): The requested loan may exceed the bank's maximum leverage.
·Occupancy: High vacancy or unstable rental income can create underwriting concerns.
·Property type: Certain banks limit exposure to hotels, restaurants, special-purpose properties, or transitional assets.
·Loan size: The request may fall below the lender's minimum or exceed its lending capacity.
·Borrower financials: Liquidity, credit history, global cash flow, or experience may not satisfy underwriting standards.
·Portfolio concentration: The bank may already have substantial exposure to a particular property type or geographic market.
A decline based on bank policy can be very different from a decline based on fundamental property economics.
The key is understanding the reason for the decision before approaching another lender.
7 Commercial Real Estate Financing Alternatives Worth Exploring
1. Private Commercial Real Estate Lenders
Private commercial lenders can provide financing for transactions that don't fit conventional bank underwriting.
These lenders may emphasize property value, collateral quality, borrower equity, and the transaction's exit strategy rather than relying exclusively on stabilized historical cash flow.
Private financing may be appropriate for:
·Commercial acquisitions requiring quick execution
·Transitional properties
·Properties with substantial vacancies
·Short-term financing needs
·Certain cash-out refinancing transactions
Private lending often carries higher borrowing costs, shorter terms, and more restrictive exit requirements than conventional financing.
Best fit: Investors who need flexibility or speed and have a credible repayment or refinancing strategy.
2. Commercial Bridge Loans
A commercial bridge loan is typically short-term financing designed to help an investor acquire, renovate, lease up, or reposition a property before obtaining permanent financing.
Consider an investor purchasing a multifamily property with 65% occupancy.
A traditional bank might be unwilling to finance the acquisition because current cash flow doesn't meet its underwriting requirements.
A bridge lender, however, may evaluate the property's stabilized value, renovation budget, lease-up plan, and anticipated refinance.
Illustrative bridge financing scenario
Purchase price
$2,500,000
Proposed acquisition LTV
70%
Illustrative loan
$1,750,000
Initial equity before costs
$750,000
Illustration only, not a financing offer. Renovation funding, reserves, closing costs, lender fees, and the ultimate loan amount depend on underwriting.
Once the property reaches stable occupancy and cash flow, the investor may refinance into longer-term debt, subject to market conditions and lender approval.
Best fit: Value-add multifamily, retail, office, industrial, and other transitional commercial properties.
3. SBA 7(a) and SBA 504 Commercial Real Estate Loans
For qualifying business owners purchasing or improving owner-occupied commercial real estate, SBA financing can be an attractive alternative.
The two major programs are:
SBA 7(a) loans
SBA 7(a) financing can support eligible real estate acquisitions, business acquisitions, equipment, refinancing, and working capital.
For standard 7(a) loans, the maximum loan amount is generally $5 million.
SBA 504 loans
SBA 504 financing is primarily designed for eligible long-term fixed assets, including owner-occupied commercial buildings and major equipment.
A common 504 structure includes financing from a third-party lender, a Certified Development Company, and a borrower contribution.
Under a typical structure, the borrower contributes at least 10%, although certain projects require higher equity contributions.
For existing buildings, SBA owner-occupancy requirements generally require the operating business to occupy at least 51% of the property. Different requirements apply to new construction.
Best fit: Eligible small businesses, medical practices, manufacturers, professional service firms, and owner-users seeking long-term real estate financing.
SBA programs are not generally intended for passive investment real estate. Eligibility, use of proceeds, and program terms must be verified under current SBA rules.
4. Commercial Real Estate Debt Funds
Debt funds provide capital to commercial real estate investors through professionally managed investment vehicles.
They may offer financing for acquisitions, construction, repositioning, and transitional properties.
Debt funds can be especially relevant for larger or more complex transactions that fall outside traditional bank underwriting.
Potential advantages include flexible loan structuring, experience with transitional assets, and the ability to evaluate complex business plans.
However, borrowers should carefully evaluate interest rates, fees, covenants, extension provisions, and exit requirements.
Best fit: Experienced investors, developers, and sponsors executing sophisticated commercial real estate strategies.
5. CMBS Loans
Commercial Mortgage-Backed Securities (CMBS) financing provides another potential source of capital for qualifying commercial properties.
Rather than holding every mortgage directly on a bank balance sheet, CMBS loans are typically pooled and securitized for investors.
CMBS financing may be available for qualifying stabilized properties, including multifamily, retail, office, industrial, and hospitality assets.
Potential benefits include competitive fixed-rate financing and longer-term debt structures.
Important considerations include:
·Prepayment restrictions
·Yield maintenance or defeasance
·Cash management provisions
·Reserve requirements
·Loan servicing complexity
Best fit: Investors with stabilized, income-producing properties seeking long-term financing.
6. Life Insurance Company Commercial Mortgages
Life insurance companies are significant providers of commercial mortgage financing.
These lenders often focus on stabilized properties with strong cash flow, experienced sponsorship, and durable collateral value.
Life company financing can offer attractive long-term fixed-rate structures for qualifying transactions.
These lenders frequently prioritize conservative leverage, property quality, and predictable income.
Best fit: Stabilized multifamily, industrial, retail, office, and other institutional-quality properties.
7. Credit Unions and Specialized Commercial Lenders
Credit unions and specialized nonbank lenders can also provide commercial real estate financing.
Depending on their lending authority and programs, credit unions may offer financing for owner-occupied buildings, investment properties, and commercial refinancing.
Specialized lenders may focus on particular property types or financing situations, such as:
·Multifamily investment properties
·Self-storage facilities
·Medical office buildings
·Industrial properties
·Hotels and hospitality assets
·Construction and development
·Commercial cash-out refinancing
A lender specializing in a particular property type may understand risks and opportunities that a general commercial lender is less comfortable underwriting.
Best fit: Borrowers seeking a financing solution aligned with their specific property type, loan size, and investment objectives.
Comparing Commercial Real Estate Financing Options
Financing source | Typical use | Key consideration |
Traditional banks | Stabilized and owner-occupied properties | Bank credit policies |
Private lenders | Flexible or time-sensitive transactions | Higher costs |
Bridge lenders | Value-add and lease-up projects | Short maturity |
SBA 7(a)/504 | Eligible owner-occupied business property | SBA eligibility |
Debt funds | Complex and transitional transactions | Fees and covenants |
CMBS lenders | Stabilized investment assets | Prepayment restrictions |
Life companies | High-quality stabilized properties | Conservative underwriting |
Credit unions | Eligible commercial borrowers | Institution-specific limits |
No single financing source is automatically the best choice. The right lender depends on the transaction, borrower, and long-term strategy.
Understanding the Three Metrics That Drive Commercial Lending Decisions
Regardless of which commercial real estate financing option you pursue, lenders typically focus on three important metrics.
Debt Service Coverage Ratio (DSCR)
DSCR measures the property's ability to cover its debt payments.
\[ DSCR=\frac{\text{Net Operating Income}}{\text{Annual Debt Service}} \]
For example, if a property generates $180,000 in annual NOI and requires $135,000 in annual debt service:
\[ DSCR=1.33x \]
A 1.33x DSCR means the property generates approximately $1.33 in NOI for every $1 of annual debt service.
Loan-to-Value Ratio (LTV)
LTV measures the proposed loan amount relative to the property's appraised value.
\[ LTV=\frac{\text{Loan Amount}}{\text{Property Value}} \]
A $1.5 million loan on a property valued at $2 million represents a 75% LTV.
Debt Yield
Debt yield measures NOI relative to the loan balance.
\[ Debt\ Yield=\frac{\text{Net Operating Income}}{\text{Loan Amount}} \]
A property producing $150,000 in NOI with a $1.5 million loan has a 10% debt yield.
These metrics help lenders assess different aspects of credit risk. Underwriting standards vary significantly by lender and property type.
Why Working With a Commercial Mortgage Broker Can Make a Difference
Approaching commercial real estate financing through a single bank means relying on one institution's products, policies, and appetite for risk.
A commercial mortgage broker or capital advisor can help borrowers evaluate financing across multiple lending sources.
An experienced advisor can help:
1.Evaluate the property's financial performance and financing requirements.
2.Identify lenders that finance the relevant property type and transaction.
3.Structure the request around realistic leverage and debt service.
4.Prepare a complete financing package.
5.Compare lender proposals beyond the quoted interest rate.
6.Coordinate underwriting, due diligence, and closing.
Importantly, the lowest advertised rate does not always represent the best financing structure.
Borrowers should evaluate total borrowing costs, amortization, maturity, prepayment penalties, recourse provisions, reserves, and closing requirements.
How the CommLoan Empower Program Helps Commercial Borrowers
As a capital advisor with the CommLoan Empower Program, I help commercial real estate investors and business owners explore financing options beyond a single financial institution.
The CommLoan platform provides access to a marketplace of more than 700 lenders, creating opportunities to identify financing programs that may better align with a borrower's transaction.
Using CommLoan's CUPID™ technology and capital advisory resources, we can evaluate commercial financing opportunities based on important transaction characteristics.
Our goal is to help borrowers identify appropriate financing options while navigating the complexities of commercial lending.
Whether you're purchasing an apartment complex, refinancing a retail center, acquiring an industrial building, or financing an owner-occupied property, the process begins with understanding the transaction.
Access to a broad lender network does not guarantee loan approval or specific terms. Every request remains subject to lender underwriting.
What to Do When Your Bank Declines Your Commercial Loan
If your bank declines your commercial financing request, don't immediately assume the transaction is dead.
Start by determining exactly why the bank declined the loan.
Was the issue occupancy? DSCR? Loan size? Property type? Borrower liquidity? Portfolio concentration?
Next, review the financial information supporting your request.
A complete financing package should generally include:
·Property description and financing request
·Current rent roll and trailing 12-month operating statement
·Historical property financials
·Purchase contract or existing mortgage statement, as applicable
·Borrower financial statement and liquidity documentation
·Property improvement or stabilization plan, if applicable
·Supporting appraisal, environmental, and property documents when available
Once the financing package is organized, an advisor can help determine whether alternative lending sources may be appropriate.
The objective isn't simply to submit the same declined loan request to more lenders.
It's to identify the financing structure that fits the actual transaction.
Frequently Asked Questions
Can I get a commercial real estate loan if my bank declined me?
Possibly. A decline from one bank does not automatically disqualify a borrower from financing elsewhere. Alternative lenders may have different requirements for occupancy, property type, cash flow, and collateral. However, material credit or feasibility problems may affect all lending options.
Are private commercial real estate loans more expensive than bank loans?
Often, yes. Private financing frequently carries higher rates and fees because it may involve greater flexibility, shorter terms, or additional risk. Actual costs depend on the lender and transaction.
Can I finance a commercial property with high vacancy?
Potentially. Certain bridge lenders and debt funds specialize in transitional properties. They will generally evaluate the business plan, borrower equity, property value, and realistic stabilization strategy.
What is the best commercial real estate financing option for a small business?
For an eligible owner-occupied property, SBA 7(a), SBA 504, conventional bank financing, and certain credit union programs may be worth comparing. The best option depends on business cash flow, project cost, eligibility, and intended use.
How do I find alternative commercial real estate lenders?
A commercial mortgage broker or capital advisor can help identify lenders that specialize in your transaction type and compare available financing structures.
Final Thoughts: Expand Your Financing Options, Not Just Your Lender List
Commercial real estate financing is not a one-size-fits-all business.
Traditional banks remain an important source of commercial capital, but they are only one part of the broader lending marketplace.
Private lenders, bridge lenders, SBA programs, debt funds, CMBS lenders, life insurance companies, and specialized lending institutions can provide additional options for qualifying transactions.
The most effective financing strategy begins with understanding the property, borrower, and investment objectives.
A bank's credit box should not be the only factor determining your financing strategy.
Ready to Explore Your Commercial Real Estate Financing Options?
Bill Rapp, CCIM Capital Advisor | CommLoan Empower Program
Whether you're acquiring, refinancing, or repositioning commercial real estate, explore financing options beyond your local bank.
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
Main Office:
Medallion Funds
[email protected]
11920 Southern Highlands PKWY Suite 302Las Vegas, NV 89141
Texas Complaint and Recovery Fund Notice
All Rights Reserved Copyright © 2021 - Bill Rapp The Mortgage Viking | NMLS #228246