ATTENTION: For Those who are serious about Getting Pre-Qualified FAST!
Bill Rapp, Mortgage Originator: NMLS 228246
"Brokers Are Better.
Better Pricing, Better Service!"
Subscribe To My List Below To Get Your Mortgage Quote Now!
Simply enter your name and email below:
WITH PROVEN STRATEGIES & PROVEN RESULTS
HERE'S WHAT MY CLIENTS SAY:
What People Are Saying:
Excellent Service
Bill is an exceptional loan officer. He helped us to purchase our home with very personal and professional service. He helped us navigate the whole process from start to closing without any problems. We didn't think we're qualified to purchase a house, but Bill went above and beyond to find a way to help us achieve our goal. He always responded very quickly with our requests, he would come back with different options with comparison chart to clearly indicate how much we need for down payment, monthly payments, interest rates, closing costs etc.
We would highly recommend Bill to anyone in need of lending services. In fact, we have already recommended Bill to one of our friends on purchasing a house.
--- David Chan - Houston, TX
Bank Statement Lending!
William Rapp of Network Funding, L. P. was very professional and I felt comfortable in dealing with him. I will definitely recommend him to family and friends.
--- Ian F - Missouri City, TX
Professionalism - Expert In Home Style Loan
Bill is an expert in the topic, his explanations and online material make a difference and he is always there from the beginning to the end. He is committed to make thing happen.
--- Felipe Caldern & Carolina Angel Gutierrez
Great Service!
Bill Rapp's handling of our loan (even though out of state) was unparalleled to any service I have been through prior, including 3 different real estate transactions and multiple refinances. Extremely quick close, with great options and flexibility for my families needs. All around A+
--- Chris & Beth Sheehan - San Jose, CA
Knowledgeable and Responsive!
Bill was a pleasure to work with and he made the loan process fairly easy. He answered all questions I had very quickly and was straight forward in doing it. I would recommend Bill to others.
--- Wes Brady - Richmond, TX
Very professional and always returned our calls!
Bill takes a lot of pride in his job and is very dependable. They were very patient and understanding. He went out of his way and explained all my questions and concerns. They were very professional and returned my phone calls and emails. He did a great job and I fully recommend him.
--- Therese, Malcom & Shirley Teixeira - Katy, TX
Great Job!
Bill helped us out from beginning to end of loan process. The loan closed in a timely manner as Bill worked hard with bank to get our to the final steps.
--- Kamal & Theresa Wilson - Hartford, CT
Avid Problem-Solver and Absolute Pleasure to Work With!
Bill Rapp worked very hard to ensure that we closed our loan and were able to move into our new home. He always had alternatives to any problems we encountered while closing. He worked with us from the beginning identifying solutions to any problems that we were having. He was an absolute pleasure to work with!
--- Nikita Rayani & Sanit Tejani - Houston, TX
Awesome to work with!
Being a first-time buyer I came in with lots of questions and concerns. Bill was always available for any questions I had and answered everything to my satisfaction. Bill made the loan process so painless that I could still concentrate on other things. We ended up closing early which made things even better. If you are in need of a lender and want someone who is very approachable and stays on top of your loan then Bill is your guy.
--- Cesar Raya - Richmond, TX
Loan Declined by my bank, and he saved the day!
Bill, did an amazing job helping me close on my house. He took the reigns and reassured me the best route to take to help close. He was accountable, thorough and trustworthy. I will continue to work with Network Funding, L.P. when it comes to home buying in the future because of the quality of service Bill gave.
--- Jacob Smith - Boerne, TX
Bill Rapp Will Definitely Make It Happen!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Corinne Wilson - Roselle, NJ
Knowledgeable, Honest, Trustworthy, and Reliable!
"I will definitely keep you in mind. If anyone I know needs financing, I will send them your way!"
--- Jon & Andrea Saleem, CRPC Financial Advisor - Houston, TX
Best Dam Mortgage Guy a man could know!
"Hands down the best loan experience to date!"
--- Gabe & Chelsea Jackson - Pearland, TX
Phenomenal, Hard Working and Never Quits!
Had a stupid foreclosure that could have been avoided if ex’s attny would have sent my buy out offer. So Bill was able to push this through with a 4 year foreclosure. He worked his butt off, was very diligent with his communication; and was very professional talking to me even when I was screaming and/or crying at him. Highly recommend this lender. He really go to the ends of the earth to help you!
--- Liz Keeter - Harlingen, TX
Exceptional customer service!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Isha Lopez & Mauricio Garcia - Houston, TX
Service with a capitol S
Bill went above and beyond at every turn. He worked late on Saturday, he worked late all the time. We wanted to close ASAP and he really helped make it happen for us.
--- Jeff & Wendy Heger - Houston, TX
Best Buying Experience!
I would would highly recommend going with Network Funding LP. As a first time home buyer I didn't know what to expect. Bill Rapp was very helpful in answering all my questions and guided me through all ghe steps. I couldn't have asked for a better buying experience!
--- Tabitha Turner - Humble, TX
Would recommend him and use him again!
Very involved and professional . Kept me informed and up to date on everything that was going on Went with me closing and was very helpful and knowledgeable.
--- Kathy Ward - Houston, TX
Great experience!
Well I meet bill back in December 2016 he got recommended by my real estate agent we had a house in sight and started the process to get approved but we fail due to my work history and credit bill told me not to give up and put me in contact with a credit repair company they help me bring my score up and bill walk me thru the process of getting a new line so this time around we got approved before looking for our house after we found it we still had a couple of hick up but with bills help on Sunday 6-18-17 to be exact Father's Day bill called me to give me the great news that we had got approved and the closing date was as scheduled bill was more than just a lender to my family he became a friend and I'm alway going to have him in mind for any other financial situation.
--- Alejandres Felimon - Richmond, TX
I really liked his attitude!
I wouldn't usually say this but the way he had handled my mortgage was really pleasant. I personally enjoyed the time spent with him while we discussed feasible rates. He's a great man with a great personality and he offered really low interests as well. Definitely recommend him to others.
--- Tom Troiano - Atlantic City, NJ
He's nothing short of a miracle!
I'm a self-employed businessman and had him figure out the mortgage of the house after 30% down payment. The interest rates I received were incredibly low given what I had thought of earlier. One other important thing to note was that I hadn't really taken any loans earlier, so I had no credit history. He helped me out with all that as well so I can't really call him anything else but a miracle.
--- Fran Suarez - Cleveland, OH
He's really helpful!
I made a bid to him and the very same day he gave me an offer which I couldn't resist. It was too intimidating with those incredibly low interest rates and all, thoroughly recommend him.
--- Kenny Mickle - Houston, TX
Expeditious!
Bill was very expeditious and made it real easy going through the loan process. I felt he was on top of things.
I deal with investment properties and will more than likely call on him again.
--- Wayne King - Pensacola, FL
Bill was great!
Bill made us feel like a friend all the way thru the process. He was patient and explained everything he needed clearly. He was available ANYTIME we had questions or needed more information. Hopefully we won’t go thru this process again anytime soon, but if we do - we’d choose Bill! =)
--- Barbra & Nick Grimmer - Austin, TX
Great broker!
Bill was a great broker to work with. As first time home buyers we had many questions about the process, Bill took the time to help us even calling us back on weekends with answers. I would not hesitate to recommend him to anyone looking for a broker to work with.
--- Murray & Lisa Turner - Pensacola, FL
Outstanding service!
I couldn't have been more pleased with Bill's level of service. He made what is typically a lengthy, arduous process far quicker and easier at every turn. I'm extremely comfortable recommending Bill to friends and family, and will definitely utilize his services again!
--- Jim Lipari - Austin, TX
Renovation Mortgage Specialist
Two little-known home renovation mortgage programs offer solutions for buyers and homeowners who want to renovate.
Fannie Mae and the Federal Housing Administration have home renovation mortgage programs that allow buyers to borrow based on what the house is expected to be worth after the home rehab is completed. Homeowners can also use both programs to refinance their existing mortgage plus the renovation costs into one loan.
FHA's 203(k) program and Fannie's HomeStyle Renovation Mortgage have been around for years. In the old days -- when most borrowers could easily get second mortgages or generous credit lines to pay for renovations -- these loans weren't as appealing as they are today.
Home renovation loans are in Demand !
"A couple years ago, there wasn't as much demand for these loans," says Bill Rapp, a senior loan originator with Network Funding in Houston, who specializes in renovation mortgages. Demand surged in the aftermath of the housing crisis, when borrowers saw them as a way to buy and renovate distressed properties.
How it works Unlike credit lines, these renovation loans require borrowers to show that the money was spent on the house. In the standard FHA 203(k) program, the borrower hires a consultant to assess the construction plan and to perform an inspection before each draw is made. A "draw" happens when a portion of the money is disbursed to the contractor. Borrowers have up to six months to finish the project and are allowed up to five draws. The HomeStyle program does not require a consultant to monitor the work, only an initial and final inspection.
Great for foreclosure hunters !
While rehab loans involve more work than traditional mortgages, they can be a great tool for those who want to buy discounted homes that need repair.
Bill Rapp says he helped a couple who bought a foreclosed house in Houston, TX for $26,000 and borrowed $136,000 to renovate the property. An appraisal estimated the home would be worth about $135,000 after the work was completed. The couple was able to take out an FHA 203(k) mortgage totaling $144,000, which covered the price of the house, renovations, and loan costs, minus a down payment.
But how do you know which loan is best? It depends on the situation.
203(k) vs. HomeStyle .
Those who don't have great credit should probably opt for an FHA 203(k). Most Fannie Mae HomeStyle lenders require a credit score above 660. To get the best rate on a HomeStyle mortgage, borrowers need to have a minimum 740 credit score, Bill Rapp says.
"If you have a 740 score and 10 percent down, a HomeStyle is definitely cheaper," she says. That's because FHA mortgages carry higher mortgage insurance premiums for borrowers who put the least amount down. FHA 203(k) home renovation mortgages have an upfront fee that is rolled into the loan amount. Less-than-stellar credit For borrowers with credit scores lower than 740, it's best to compare estimates, Bill Rapp says.
FHA does not set a minimum score requirement for 203(k) loans, but many lenders require a score of 640 or greater. There are a few exceptions, and some lenders accept scores as low as 580, Bill Rapp says.
Under the FHA's 203(k) program, borrowers can get a mortgage with a down payment as little as 3.5 percent. HomeStyle requires a minimum 5 percent down payment.
The FHA 203(k) program is available only for owner-occupants. The HomeStyle program allows investors.
How much do you need?
Another key factor a borrower should consider when deciding whether to go with a 203(k) or a HomeStyle home renovation mortgage is the size of the loan.
The 203(k) rehab mortgage has to comply with FHA loan limits. The limit varies by county but is $314,827 in most places. In high-cost areas, the limit is as high as $765,525.
You may be able to borrow more with the 203(k) than with HomeStyle if you are borrowing up to the local loan limit.
With a 203(k) loan, borrowers can get up to 110 percent of the home's appraised value, compared with 95 percent with a HomeStyle loan. Both appraisals are based on what the house is expected to be worth after repairs.
What do you want to fix?
FHA's 203(k) rehab loan does not allow borrowers to use the money for luxury items such as adding a swimming pool or a spa, but HomeStyle does.
Borrowers can opt for a streamline FHA 203(k) home rehabilitation loan if they need less than $35,000 and don't have to do any structural repairs or major landscaping work. The streamline 203(k) is similar to a standard 203(k) but is easier to get and involves less paperwork and less bureaucracy, Bill Rapp says. Streamline loans don't require the borrower to hire a consultant.
Call Bill Rapp, The Mortgage Viking, today to discuss your options 281-222-0433.
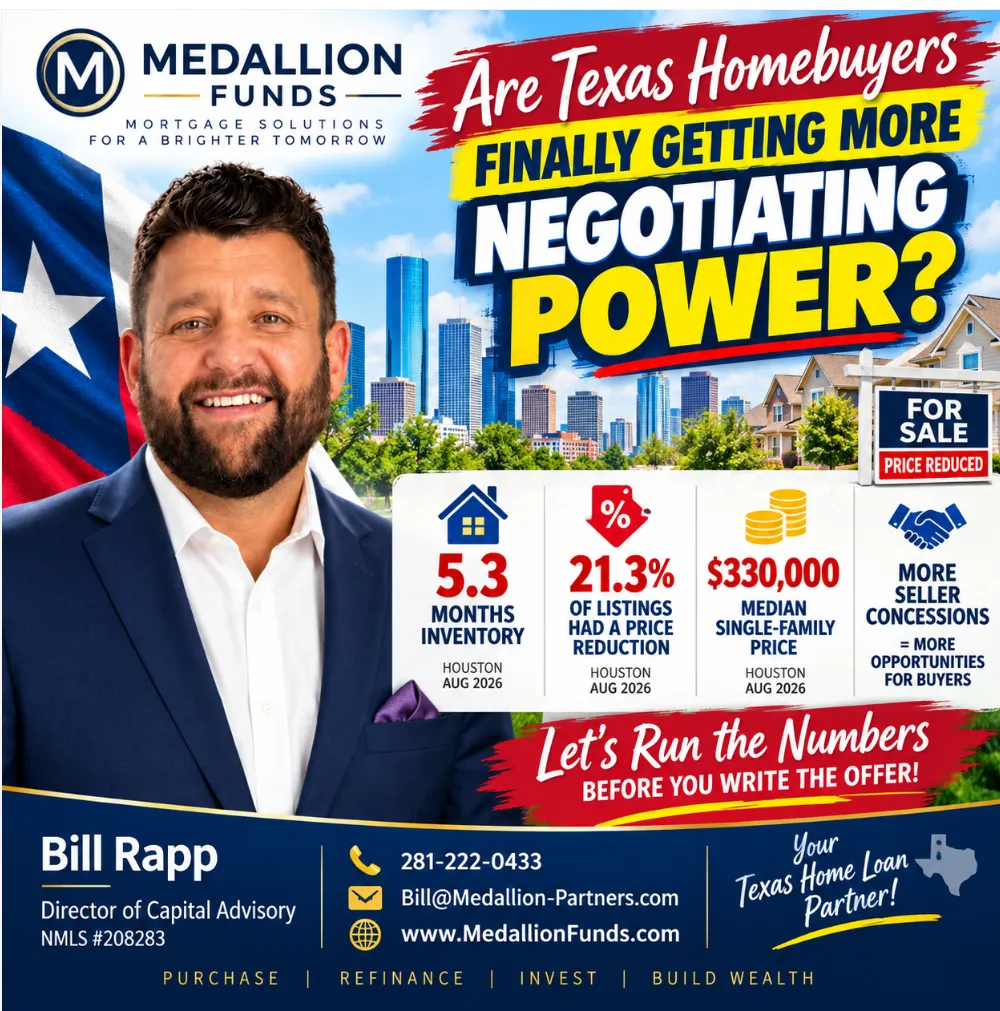
🏡 Are Texas Homebuyers Finally Getting More Negotiating Power? Here’s What the 2026 Housing Market Says 🔑
🏡 Are Texas Homebuyers Finally Getting More Negotiating Power? Here’s What the 2026 Housing Market Says 🔑
💰 Texas Housing Market 2026: More Inventory, Price Cuts & Seller Concessions Give Buyers New Leverage 🏠
________________________________________________________________________________
Are Texas Homebuyers Finally Getting More Negotiating Power?
For several years, buying a home in Texas often meant moving quickly, competing against multiple offers and having limited ability to negotiate.
In 2026, that equation has changed in many Texas markets.
More homes are available for sale, properties are taking longer to move in some areas, price reductions have become common, and sellers are increasingly willing to discuss concessions. For buyers who have been sitting on the sidelines waiting for better conditions, the opportunity may not simply be about waiting for mortgage rates to fall.
It may be about using today's negotiating environment more strategically.
The Texas Housing Market Is Shifting Toward Buyers
The shift is particularly visible in Texas' major metropolitan areas.
Redfin reported in August 2026 that sellers outnumbered buyers across Houston, San Antonio, Austin, Dallas and Fort Worth. Houston showed the largest imbalance among those metros, with sellers outnumbering buyers by nearly 130% in July.¹
That doesn't mean every Texas home is suddenly a bargain.
Desirable homes that are priced correctly and in excellent condition can still attract significant interest. But buyers increasingly have something they often lacked during the pandemic-era housing boom:
options.
And options create negotiating leverage.
Houston Buyers Have More Homes to Choose From
Houston provides a particularly useful example.
According to the Houston Association of REALTORS® August 2026 Housing Market Update:
·38,947 single-family homes were available for sale.
·Houston had 5.3 months of single-family inventory.
·Single-family sales declined 11.5% year over year.
·The median single-family sales price declined 1.5% to $330,000.
·Days on market increased from 52 to 54 days.²
Those numbers point toward a considerably more balanced environment than buyers experienced when inventory was extremely tight.
Realtor.com reported another important statistic: 21.3% of Houston listings had a price reduction in August 2026.³
For mortgage borrowers, this changing environment can create opportunities extending well beyond negotiating the purchase price.
Don't Just Negotiate the Price
One of the biggest mistakes a homebuyer can make is assuming negotiating means simply submitting a lower offer.
Price is only one variable.
Depending on the property, seller motivation, loan program and transaction structure, buyers may be able to negotiate:
Seller-paid closing costs. A seller contribution can reduce the amount of cash a buyer needs at closing, subject to the applicable loan-program limits.
Mortgage rate buydowns. Instead of focusing exclusively on reducing the purchase price, a buyer may ask for a seller credit that can be applied toward eligible closing costs or a rate buydown.
Repairs. Inspection findings can sometimes create another negotiating opportunity, whether through completed repairs, credits where permitted, or changes to the purchase price.
Closing timeline. Flexibility on possession or closing dates can sometimes become part of the negotiation.
Price reductions. Properties that have been sitting on the market or have already experienced price reductions may deserve closer analysis.
The important point is that the best mortgage strategy and the best purchase negotiation should be designed together.
A Seller Credit Can Sometimes Be More Valuable Than a Price Reduction
Consider a simplified example.
Suppose you're buying a $400,000 home.
You might initially think negotiating the price from $400,000 to $390,000 is automatically the best outcome.
But what if the seller is instead willing to provide an allowable credit that can help cover closing costs or fund an eligible mortgage-rate buydown?
Depending on your loan structure, planned holding period and available cash, the second option could potentially have a greater near-term impact on your finances.
That's why I encourage buyers to evaluate the transaction from multiple angles:
Purchase price + cash to close + monthly payment.
Don't optimize one number while ignoring the other two.
Seller Concessions Are Becoming Part of the Conversation
This isn't purely theoretical.
Redfin reported that 57.8% of Houston home sales included a seller concession during the three months ending May 2026, up 9.8 percentage points from the prior year.⁴
Concessions can include seller contributions toward certain buyer costs, repairs or other negotiated items.
The availability and amount of seller contributions depend on the loan program, occupancy, down payment, property type and transaction.
That's where mortgage planning becomes especially important.
Before making an offer, you want to understand what your financing program actually allows.
Should You Wait for Mortgage Rates to Fall?
That's the question many potential buyers continue to ask.
But waiting for a lower mortgage rate isn't the only strategy.
If rates eventually decline materially, more buyers could return to the market. That could change today's negotiating dynamics.
Nobody knows precisely where mortgage rates or home prices will go next, so buying a home shouldn't be based on predicting the market.
Instead, ask a more practical question:
Can I structure a home purchase today that makes financial sense for my budget and long-term plans?
If the answer is yes, today's increased inventory and seller flexibility may create opportunities worth evaluating.
Pre-Approval Is More Than Knowing Your Maximum Loan Amount
In a market where buyers have negotiating opportunities, mortgage pre-approval should go beyond determining the maximum purchase price.
At Medallion Funds, I want borrowers to understand different scenarios before they write an offer.
For example:
What happens if you negotiate a lower purchase price?
What happens if you keep the purchase price higher but negotiate seller-paid closing costs?
Could an eligible seller contribution be used toward a rate buydown?
How does changing your down payment affect your cash reserves and monthly payment?
What happens to the payment if you buy at different price points?
Those are financing questions that can influence how you negotiate the real estate transaction.
Three Numbers Every Texas Buyer Should Know
Before making an offer, run these three numbers:
1. Cash to Close
Know your estimated down payment, closing costs, prepaid expenses and available reserves.
2. Monthly Housing Payment
Look beyond principal and interest. Consider estimated property taxes, homeowners insurance, mortgage insurance when applicable and HOA expenses.
3. Post-Closing Reserves
Buying the house shouldn't leave you financially depleted.
Maintaining liquidity after closing can be just as important as negotiating the deal itself.
More Negotiating Power Doesn't Mean Every Seller Will Negotiate
There's an important qualification to all of this.
Texas isn't one single housing market.
Conditions can vary significantly between Houston, Katy, Dallas-Fort Worth, Austin and San Antonio—and even between neighborhoods within the same metropolitan area.
Redfin agents have also reported that well-priced, move-in-ready Texas homes can still generate multiple offers.¹
So don't assume every seller will accept a below-list offer.
Instead, use the property's individual circumstances.
How long has it been listed?
Has the seller reduced the price?
Are comparable properties sitting on the market?
Does the property need repairs?
Is the seller competing against new construction offering incentives?
Those factors can help determine where genuine negotiating leverage exists.
The Bottom Line
Yes, many Texas homebuyers have more negotiating power in 2026 than they had during the ultra-competitive housing markets of recent years.
In Houston specifically, elevated inventory, slower sales, price reductions and seller concessions are creating a more balanced environment.
But negotiating power is valuable only if you know how to use it.
Don't think exclusively about getting the seller to accept a lower price.
Think about the entire financing structure.
Price. Closing costs. Interest rate. Cash to close. Monthly payment.
Sometimes the strongest deal isn't the house with the biggest price reduction.
It's the transaction with the smartest overall structure.
If you're considering buying a home in Texas, Medallion Funds can help you evaluate your financing options before you make an offer so you understand how different purchase prices, seller concessions and mortgage structures could affect your transaction.
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
Main Office:
Medallion Funds
[email protected]
11920 Southern Highlands PKWY Suite 302Las Vegas, NV 89141
Texas Complaint and Recovery Fund Notice
All Rights Reserved Copyright © 2021 - Bill Rapp The Mortgage Viking | NMLS #228246